Insight Focus
Futures markets are signalling growing downside risk in dairy. A large NZ milk price futures trade and lower Fonterra forecast have strengthened the bearish case, but higher GDT volumes, resilient Chinese demand and inventory-building have so far prevented the expected correction. Rising freight costs and uncertainty over Brazil’s import demand further complicate the outlook, leaving traders questioning whether dairy is overpriced or simply proving more resilient than expected.
A large derivatives trade in New Zealand milk price futures has raised the possibility that one sophisticated market participant is preparing for a lower milk price environment. But the physical market is still refusing to behave like a market ready to break.
The bearish case for dairy is becoming easier to identify. Yet each expected catalyst for lower prices continues to be offset by stronger-than-expected physical fundamentals, raising questions over whether the market is truly overpriced or whether traders are simply early.
Milk Price Futures Signal Growing Downside Risk
On July 28, a 5,000-lot Exchange for Swaps trade was executed in SGX-NZX milk price futures. The size alone makes it notable. An EFS of this scale is often used by a participant seeking to manage margin exposure, and the direction of the trade has prompted speculation that it could have been linked to Fonterra, given its natural short position in milk and its recently reduced milk price forecast.
Fonterra has cut its forecast milk price to NZD 9.25/kgMS. At the time of writing, this is more than NZD 0.25/kgMS below the traded market. If the market were to fall towards Fonterra’s forecast, a 25c move across 5,000 lots would be worth around NZD 7.5 million, or roughly USD 4.4 million. That makes the trade commercially meaningful, not just technically interesting.
If Fonterra was behind the trade, it would suggest the cooperative is putting real money behind its view that the market is currently too high. Even if it was another participant, the signal is still important: someone large enough to move size appears to believe a material price move is coming.
Physical Markets Continue to Absorb Bearish Pressure
That fits with the broader bearish argument in dairy. New Zealand is moving into heavier seasonal selling, WMP volumes on GDT have increased sharply, and expectations of weaker demand have been widespread. Many market participants expected heavier New Zealand selling volumes to place greater downward pressure on prices. But that reset keeps being delayed.
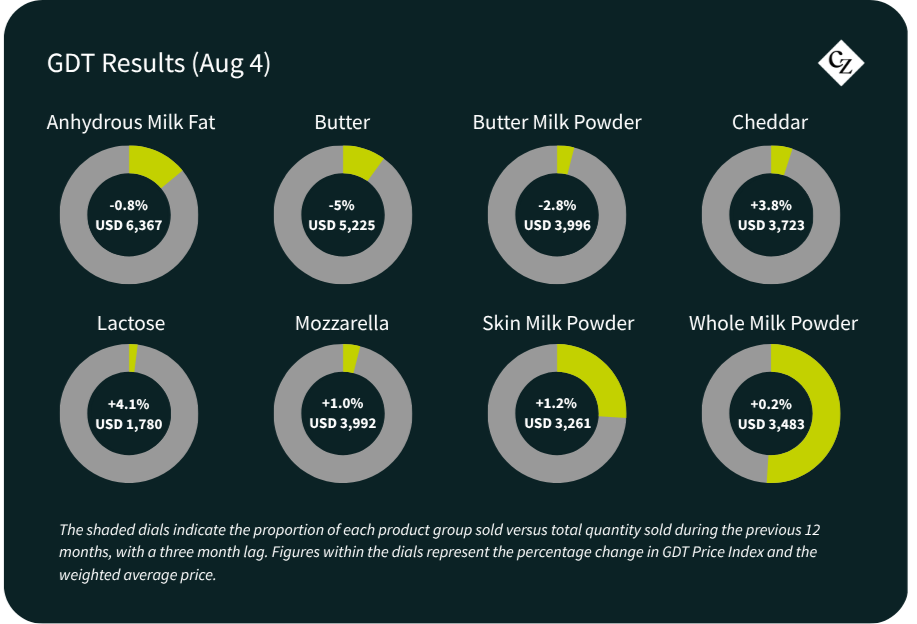
At the latest GDT event, WMP volumes were around 50% higher than the previous event, yet pricing held broadly unchanged across a wide base of winning buyers. That matters because the market was asked to absorb a much larger volume of product and did so without offering the price weakness many participants expected. This suggests that bearish pressure is being absorbed, at least for now.
Source: Global Dairy Trade
Part of the explanation may be that buyers are not only covering immediate consumption. In the current geopolitical environment, some are likely building inventory resilience. This could help explain why demand has been firmer than expected, including from China, where many had anticipated a weaker buying profile.
The freight market is also making the bearish trade harder to execute. Rates from Latin America to Algeria, a key route for ONIL WMP flows, have reportedly increased by USD 750/container, equivalent to around USD 30/tonne. For traders who sold short LATAM WMP into the June ONIL tender, this is a direct hit to the economics of the trade.
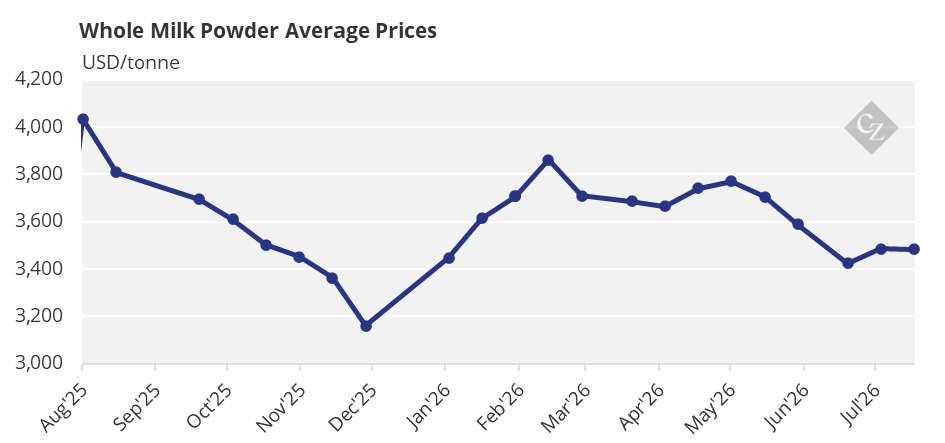
The June tender was already bought sharply, at only a slight discount to GDT at the time. Since then, the WMP market has only fallen by around USD 100/tonne, much less than many expected given rising New Zealand availability. The additional freight increase reduces the margin for error further. Anyone relying on a clean physical price decline now has to contend with higher logistics costs as well as a market that has not weakened enough.
Source: Global Dairy Trade
According to MSC, the increase reflects stronger regional cargo demand, particularly from Brazil, the withdrawal of some shipping services, and draft restrictions at public piers that have reduced available cargo capacity on certain sailings. While these factors are not dairy-specific, they provide physical evidence that logistics conditions are tightening rather than loosening on a key WMP trade route. For short sellers, higher freight costs add another obstacle to a trade that has so far delivered a smaller-than-expected decline in product values.
This creates a difficult market structure. The financial market may be signalling downside risk, but the physical market keeps creating reasons for that downside to arrive later, or in a smaller form than expected.
Will Brazil Become a Swing Buyer or a Demand Drag?
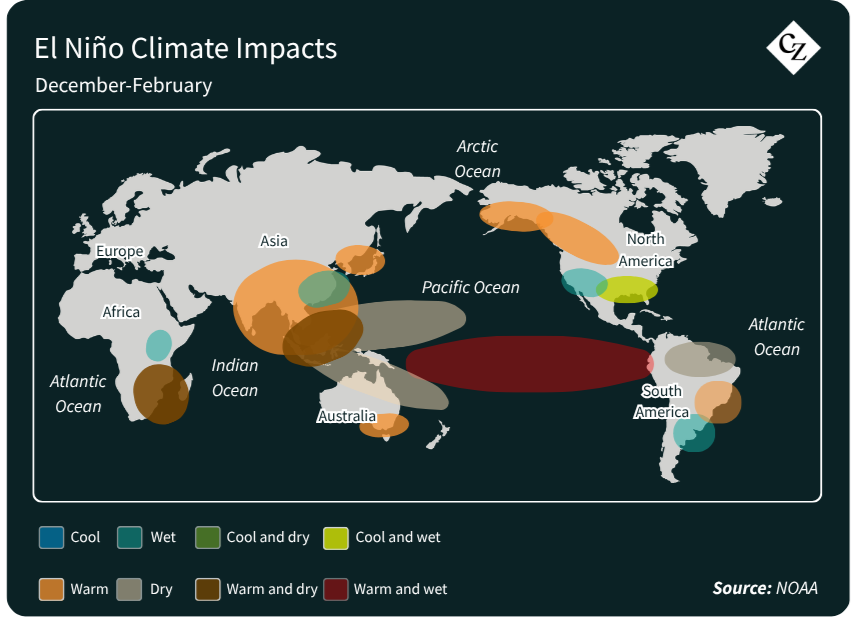
Brazil adds another complication. The usual assumption is that El Niño-related production stress could turn Brazil from a weak consumer story into an import-demand story. But that assumption may now be less reliable.
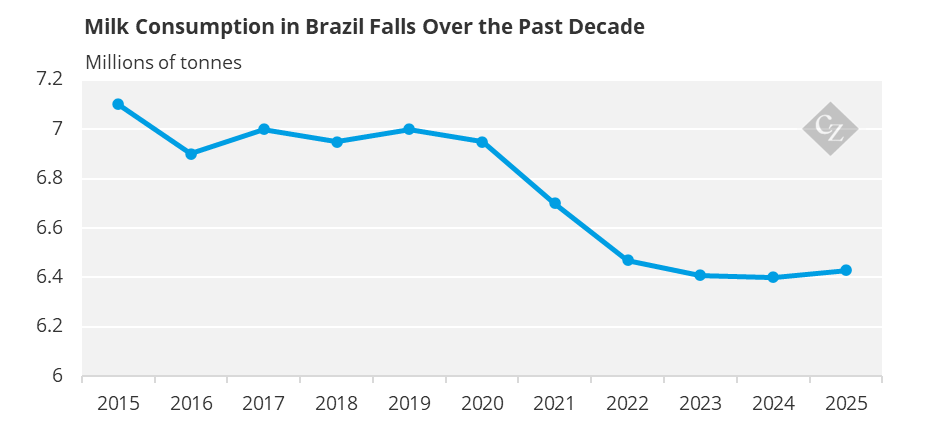
Brazilian milk consumption is already reportedly down by around 10%, while milk prices have risen by around 90%. Herd economics are under pressure and consumers are trading down. That changes the usual demand response. If consumers are already exhausted, higher prices and production stress may not generate the same import pull that the market normally expects from Brazil.
Source: Euromonitor
This is a key risk for WMP pricing. Brazil is often treated as a potential swing buyer. If El Niño affects production but the consumer side is too weak to respond, Brazil may not provide the import demand the market is waiting for. That would leave global dairy prices more exposed to any further softening in China.
The bearish case, therefore, is not wrong. There are clear reasons to expect pressure: a lower Fonterra forecast, a major EFS trade, heavier New Zealand volumes, stretched consumer affordability in Brazil, and uncertainty over whether key buyers will keep absorbing product.
But the timing is increasingly the problem. Each bearish catalyst has so far met an offsetting force. More WMP volume has been absorbed. China has remained stronger than expected. ONIL-related replacement buying is still relevant. Freight has moved against short LATAM positions. Geopolitical uncertainty is encouraging inventory resilience rather than destocking.
This raises the central market question: if every expected bearish catalyst is being absorbed, is the market actually too expensive?
That is where the recent valuation work becomes relevant. If most dairy products are already relatively cheap on a wider valuation framework, the bearish trade may require more than just higher New Zealand supply or weaker sentiment. It may need a clear demand failure, most likely from China, Brazil, or both.
For now, the market is caught between a futures signal pointing lower and a physical market still resisting the move. The biggest risk may not be whether the bearish argument is valid, but whether traders are early, underestimating the resilience of physical demand, or mispricing the cost of waiting for the correction.