Insight Focus
No.11 raw sugar futures traded higher last week. Speculators have added to their long positions by 18.k lots of longs. The wheat market has been supported by ongoing disruption to Black Sea grain exports, which continues to raise concerns over global wheat availability.
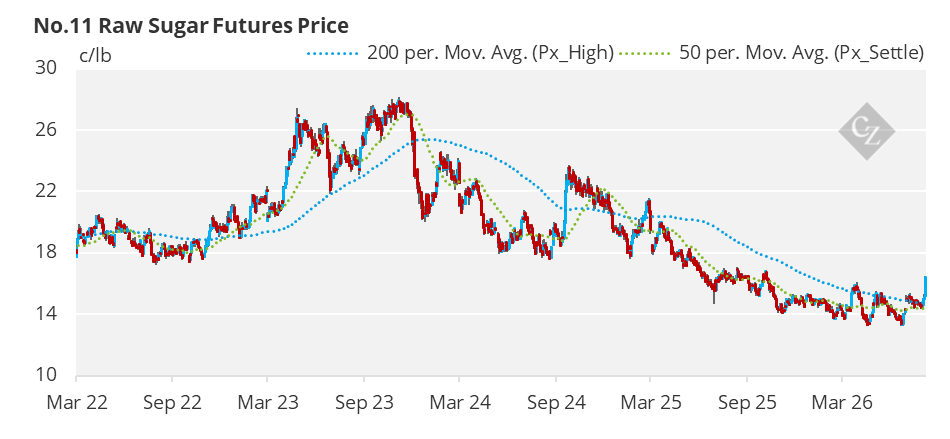
New York No.11 Raw Sugar Futures
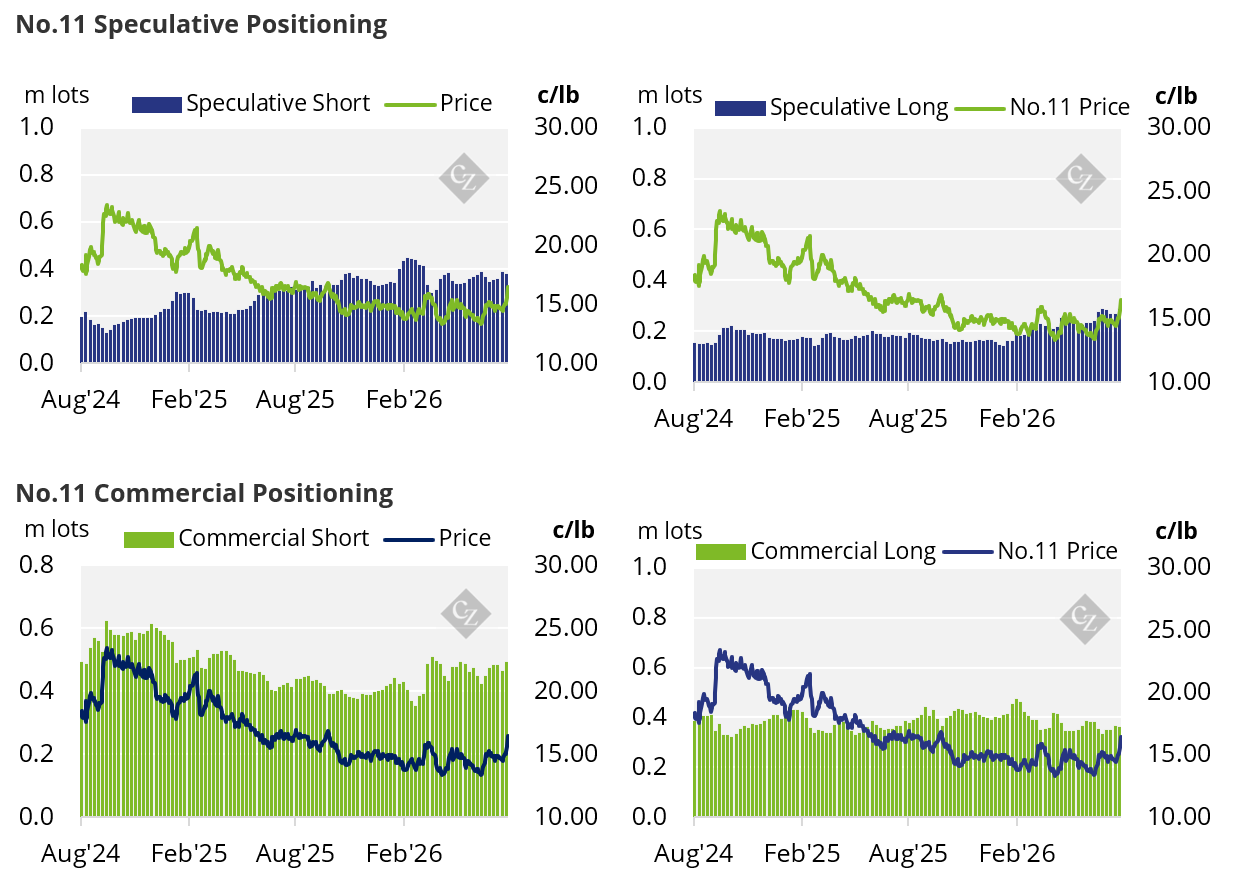
No.11 raw sugar moved higher last week, starting at 15c/lb on Monday and settling at 16.5c/lb on Friday.
Speculators opened 18.9k lots of long positions and reduced their short position by 8.9k lots.
No.11 Commitment of Traders Report (August 4, 2026)
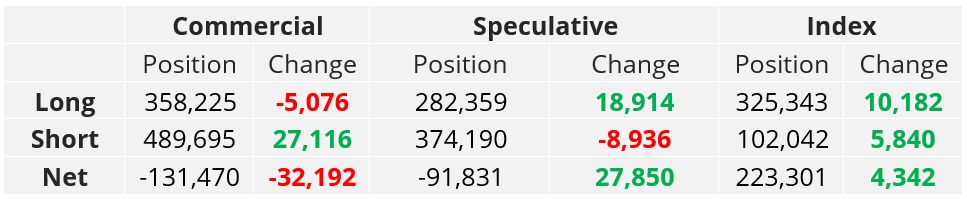
The current speculative net short position stands at -91,831.
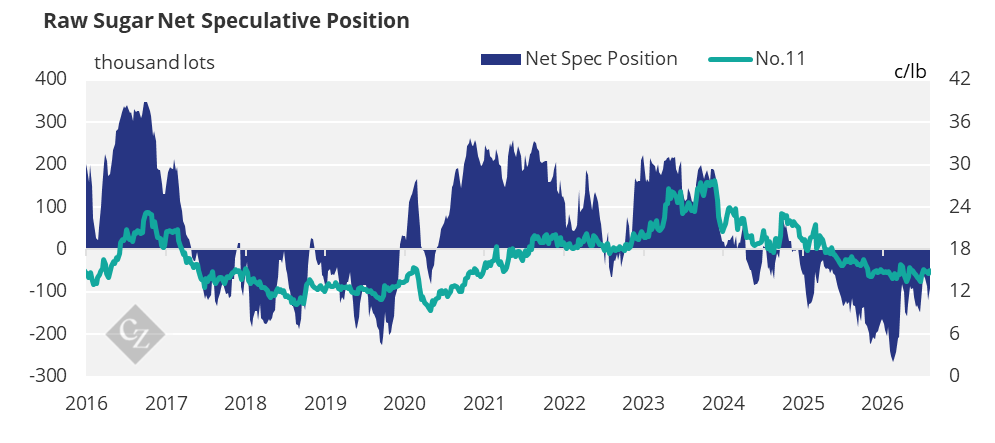
On the commercial side, end-users increased their position by 18k lots of longs whilst producers reduced their short positions by 16k lots of shorts.
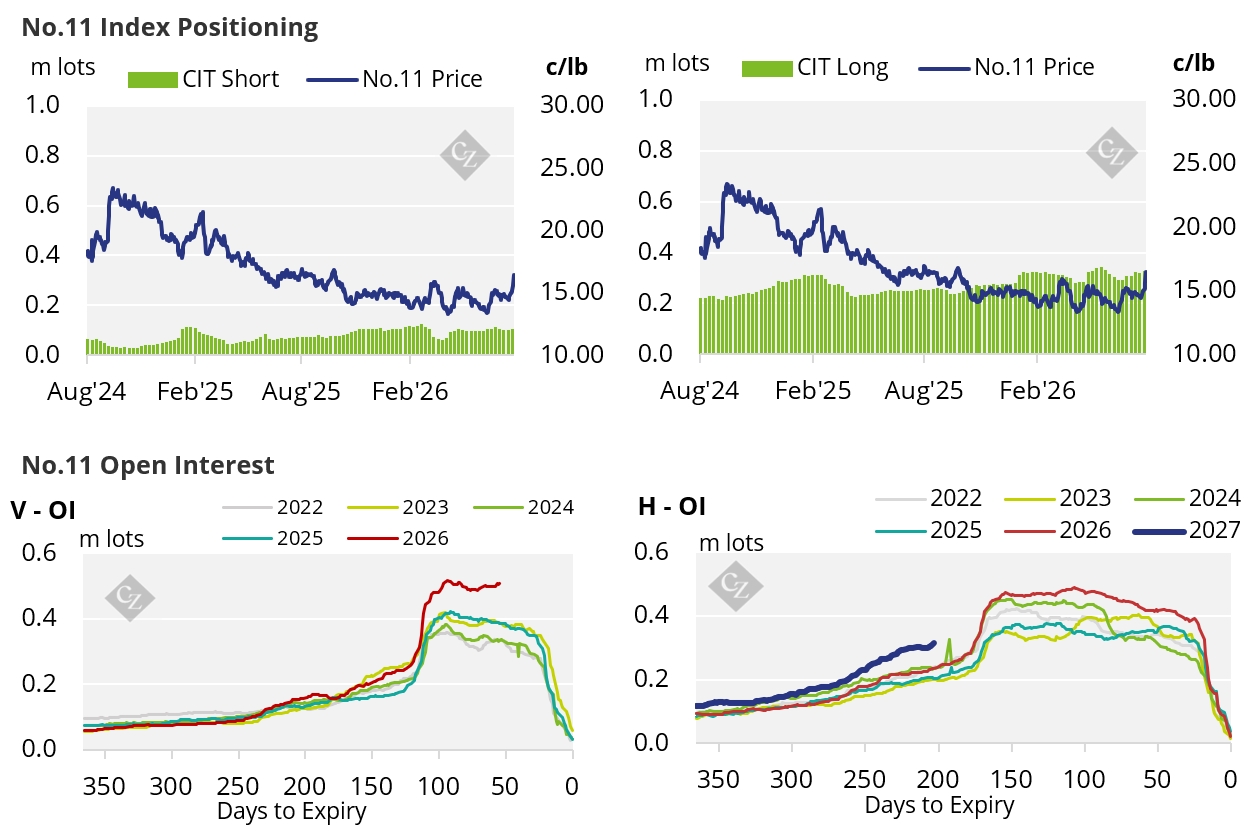
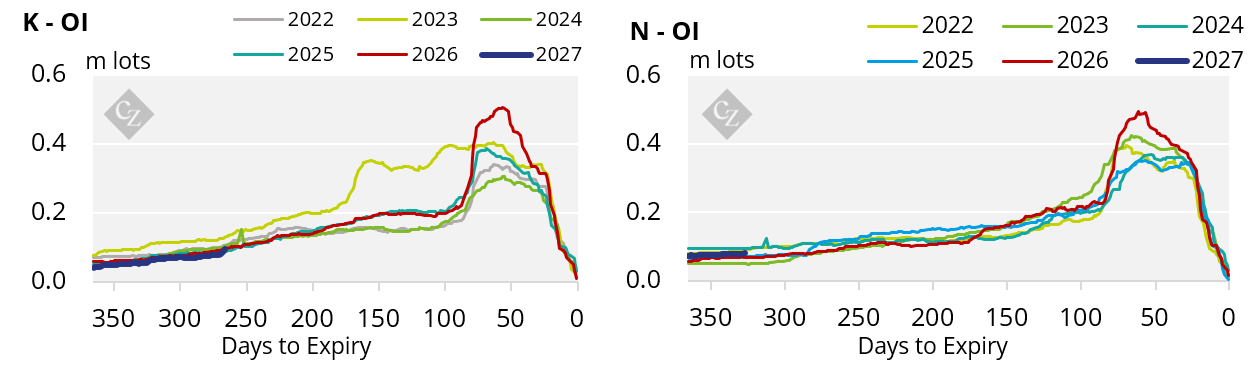
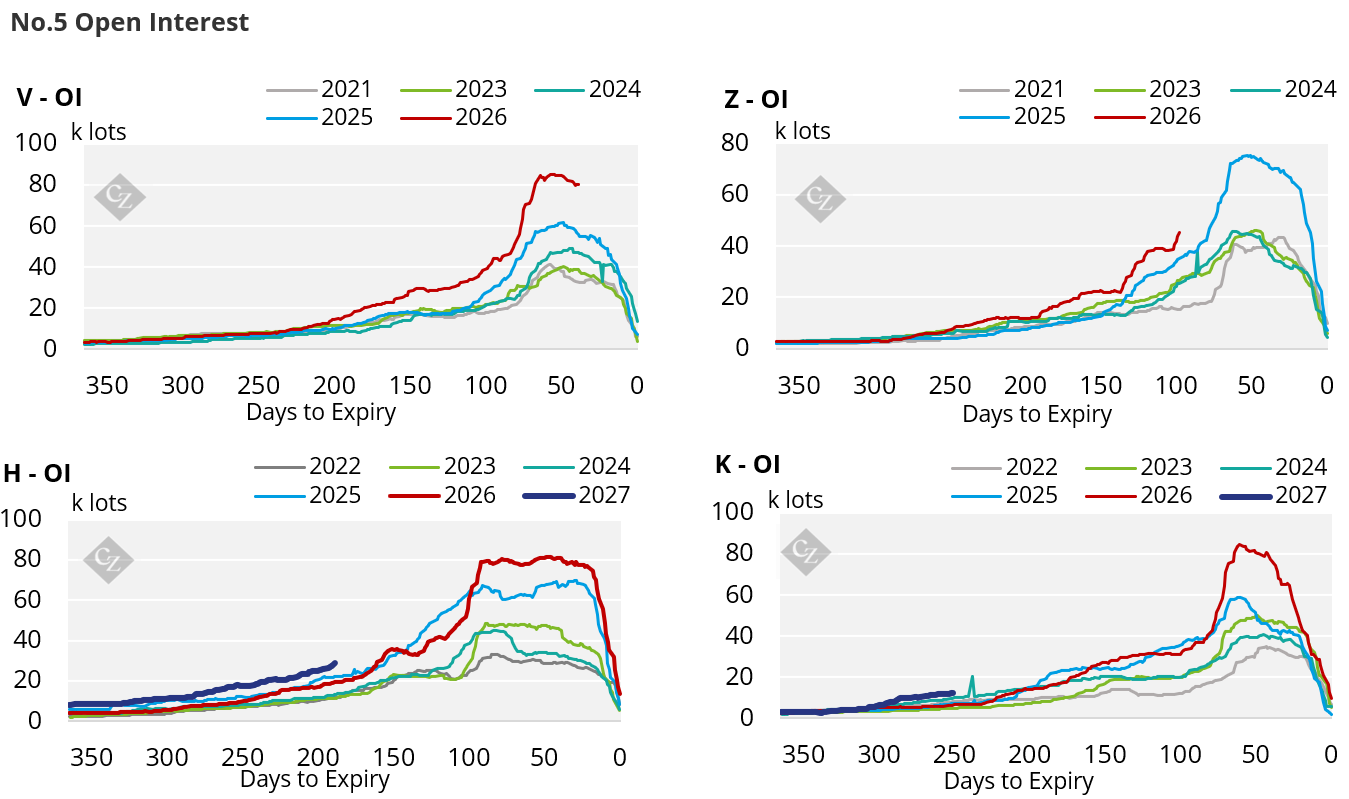
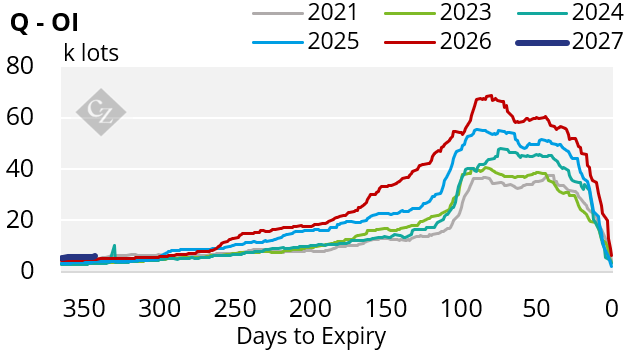
No.11 & No.5 Open Interest
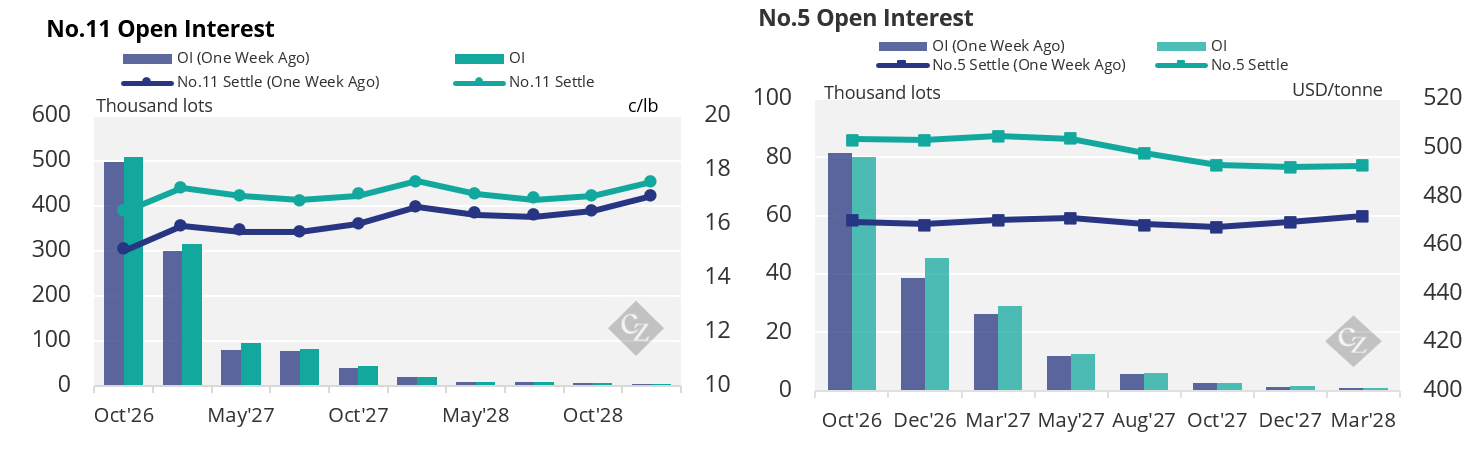
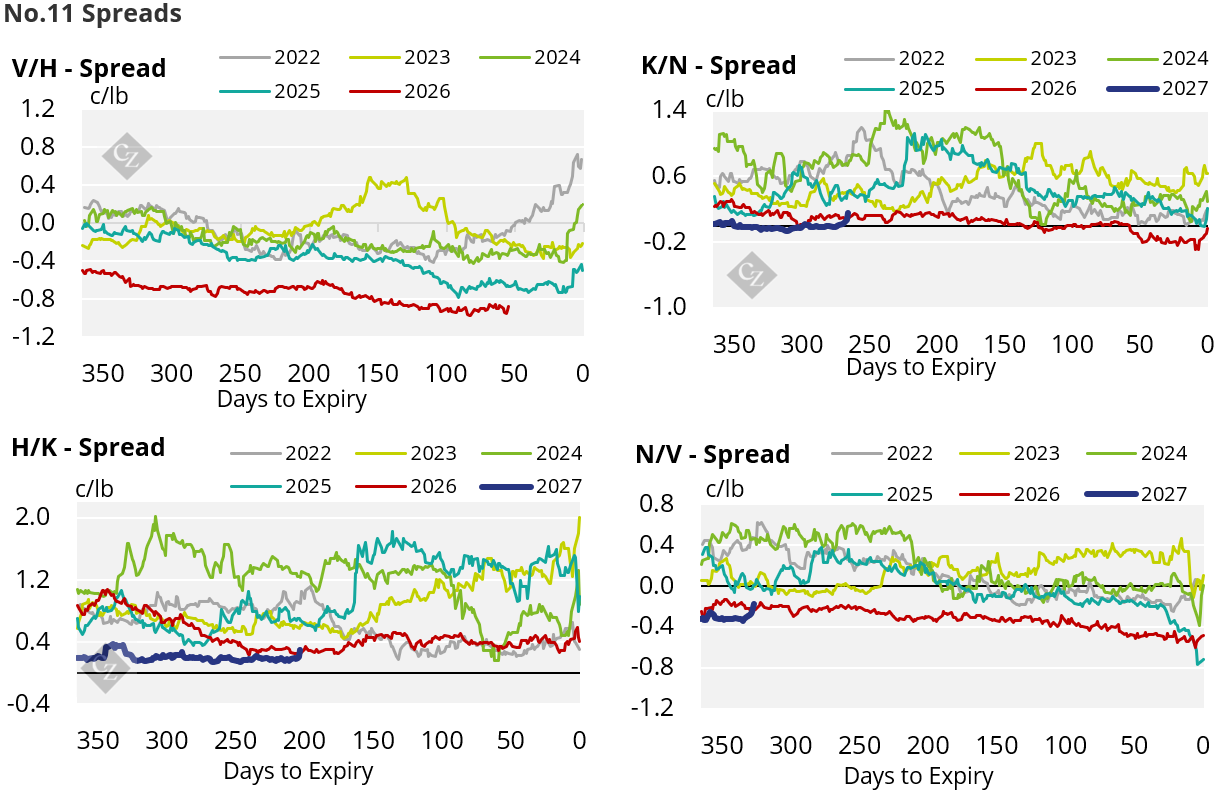
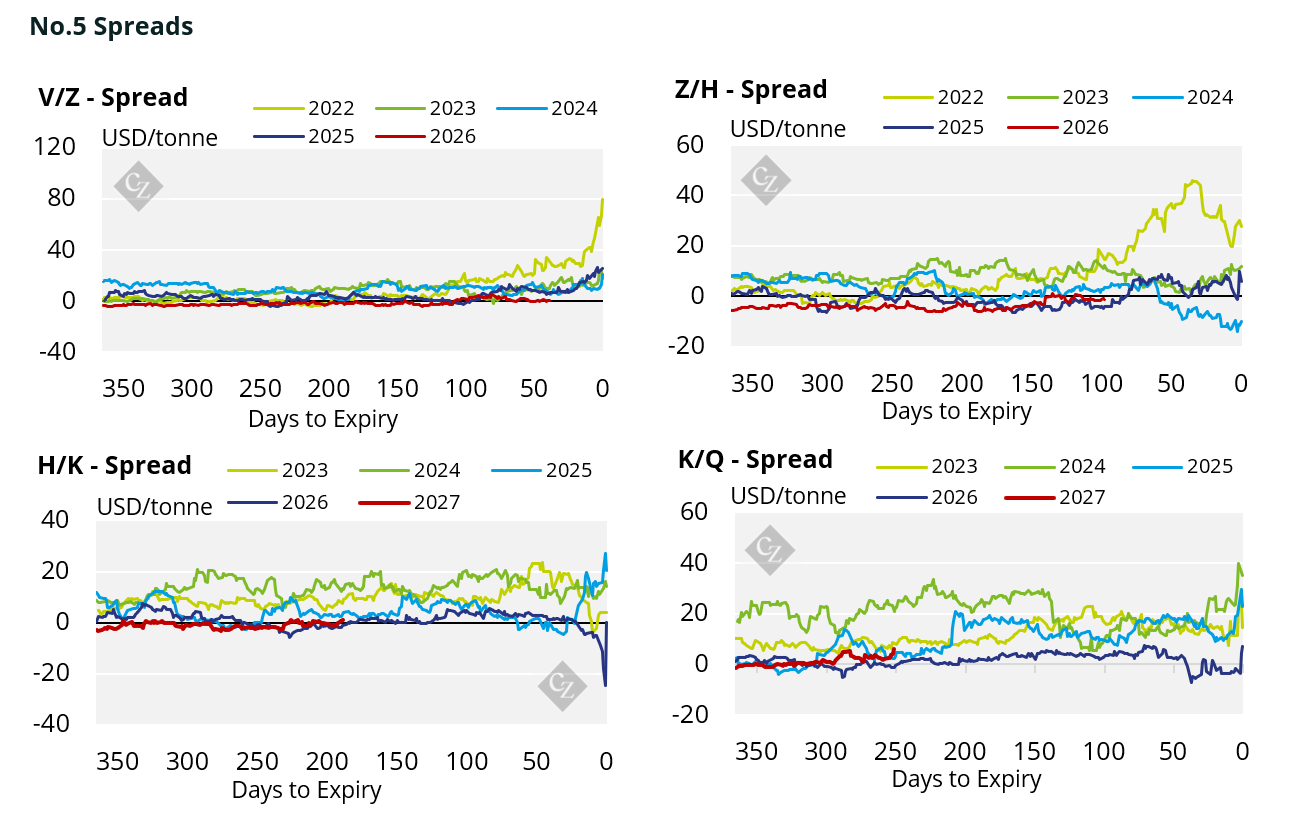
Both the No.11 forward futures curve and No.5 forward futures curve have strengthened across the board.
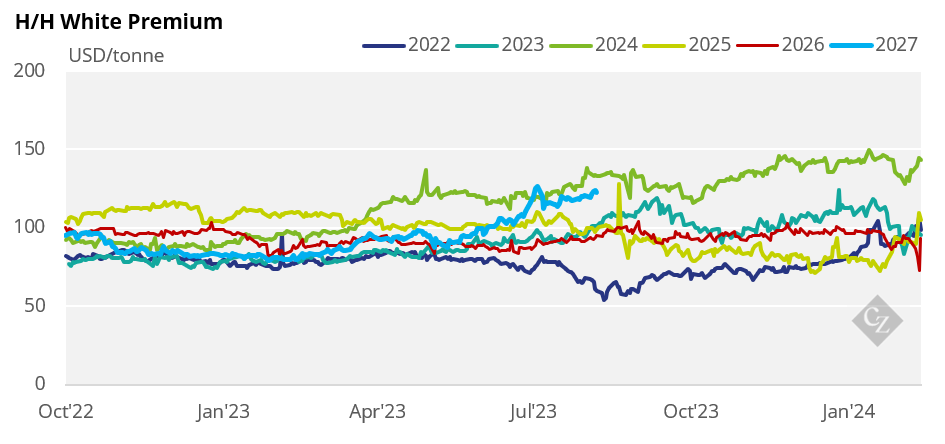
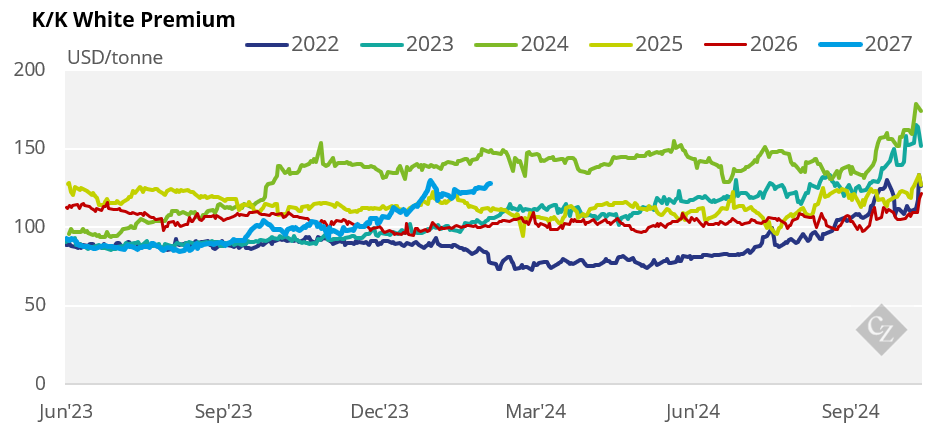
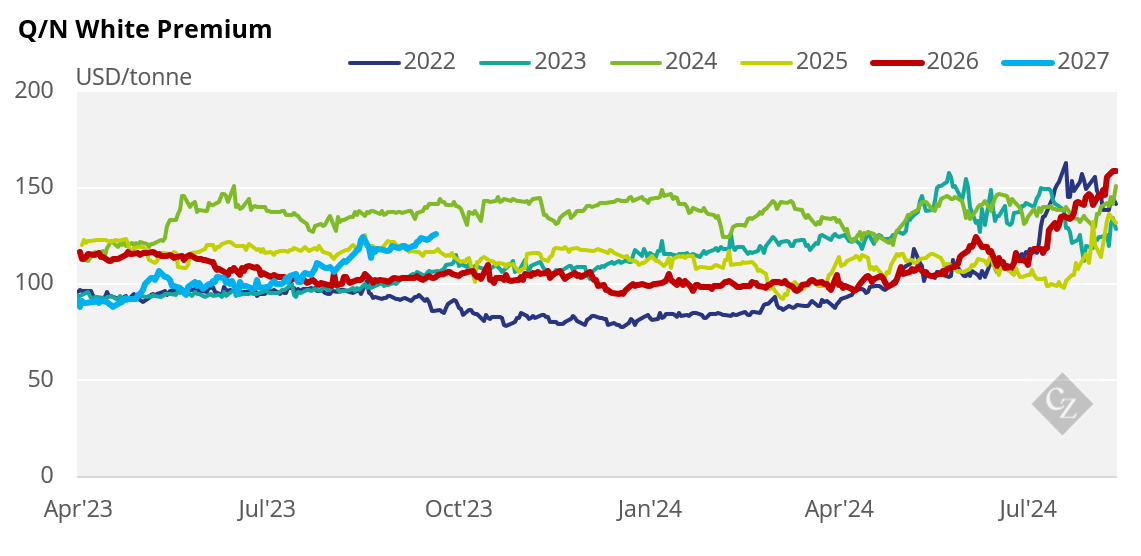
White Premium (Arbitrage)
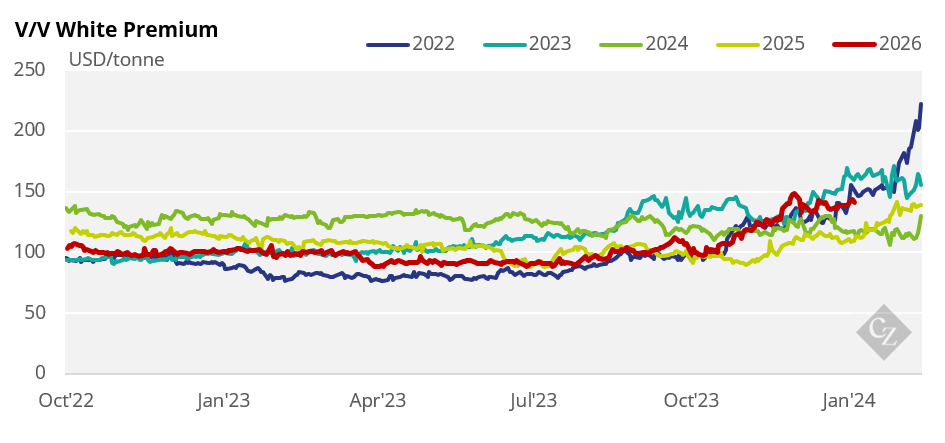
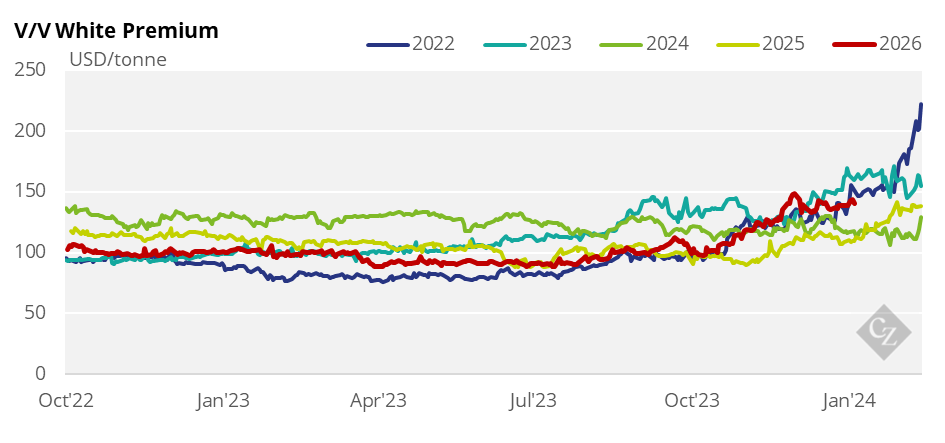
The V/V white premium rose from around USD 138.6/tonne on Monday, hit a high of USD 143.6 on Thursday and eventually settled at USD 140.7/tonne on Friday.
Wheat Futures
CBOT wheat is trading around 642.5c/bu, up 0.5% week to date and extending its winning streak to five consecutive sessions. The market has been supported by ongoing disruption to Black Sea grain exports, which continues to raise concerns over global wheat availability.
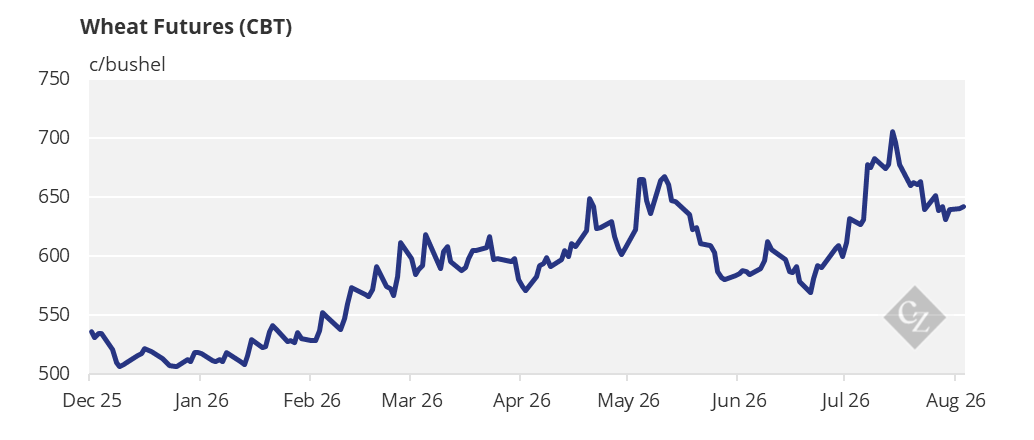
Ukraine has cut its 2026/27 agricultural export forecast from 64.4 million tonnes to 29.6 million tonnes, with wheat exports expected to fall by more than 50% following continued attacks on port infrastructure. Markets are also monitoring shipping disruptions in the Black Sea, including recent attacks on grain vessels and restrictions affecting regional grain flows.
Attention now turns to the USDA’s WASDE report, where analysts broadly expect tighter US and global grain supplies, with wheat production forecasts potentially revised lower following dry conditions in some key growing regions. A tighter stocks outlook could provide further support to prices. Providing some offset to the bullish outlook, recent rainfall has improved production prospects for Australia’s upcoming wheat crop, helping to ease some concerns around global supply. Nevertheless, Black Sea developments remain the primary driver of market sentiment in the near term.
For a more detailed view of the sugar futures and market data, please refer to the appendix below.
No.11 (Raw Sugar) Appendix
No.5 (White Sugar) Appendix
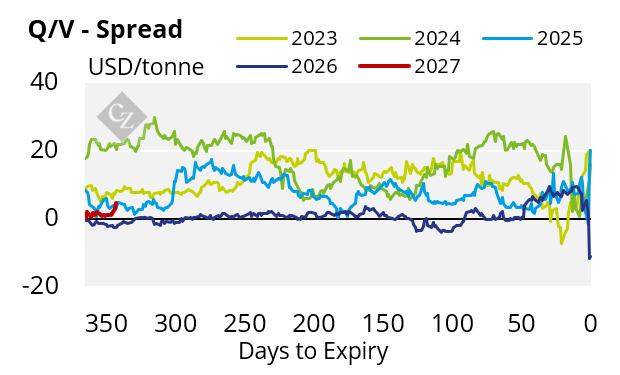
White Premium Appendix