Insight Focus
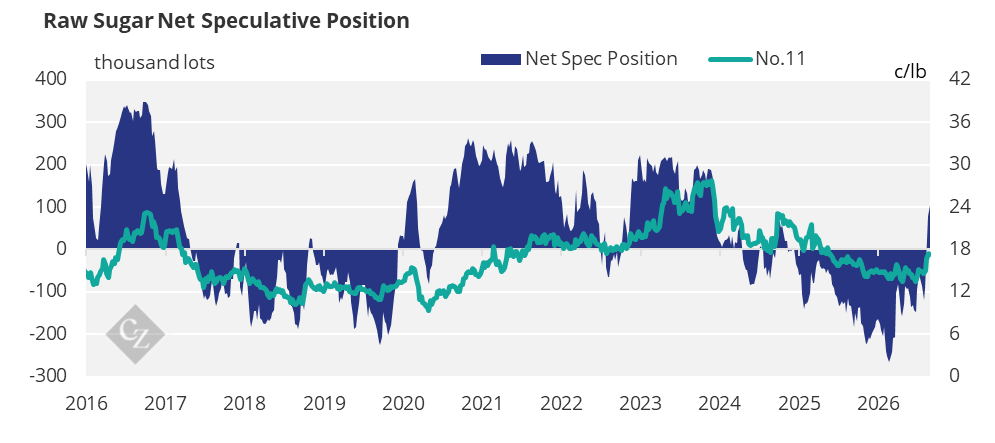
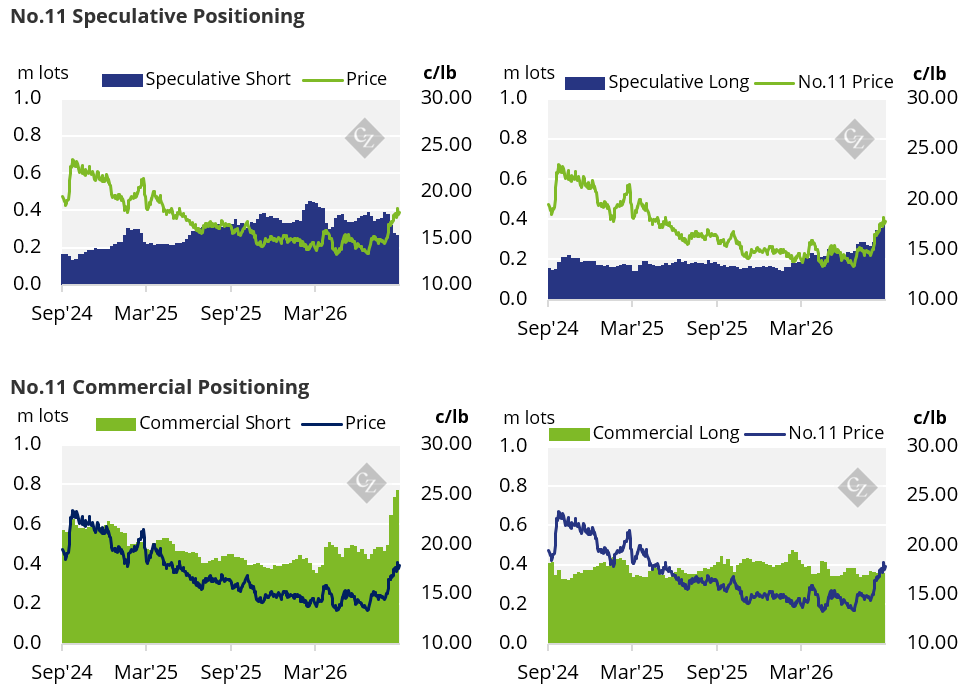
Speculators continued to build their No.11 long position and now hold a net long position of 104k lots. Producers added a further 34k lots of shorts, continuing to hedge into the price strength.
New York No.11 Raw Sugar Futures
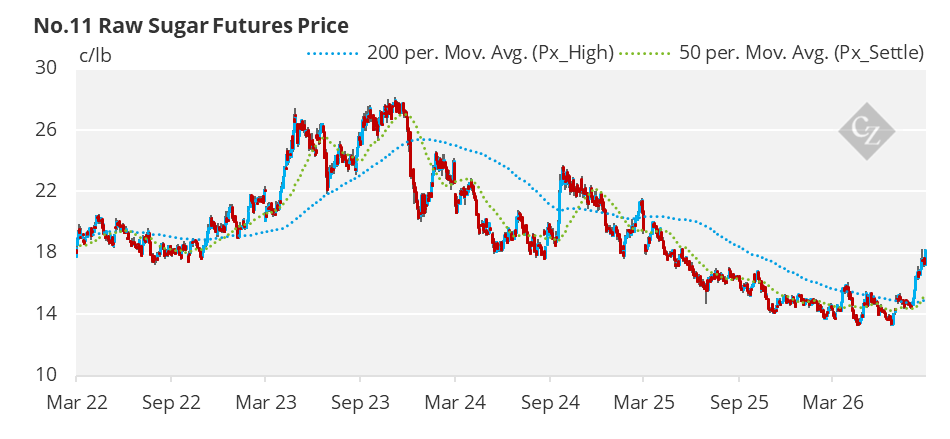
No.11 raw sugar futures started the week at 17.7c/lb and settled at 17.6c/lb on Friday. Prices climbed above 18c/lb on Thursday before dropping back down by the end of the week.
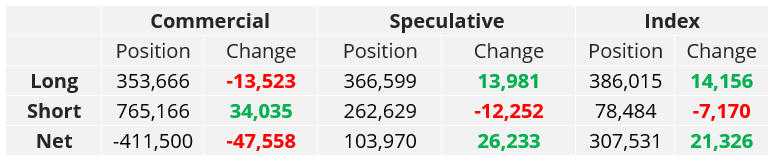
Speculators added 14k lots of longs and cut 12.3k lots of shorts in the latest reporting week. This increased their net long position by 26.2k lots.
No.11 Commitment of Traders Report (August 25, 2026)
The current speculative net long position stands at 103,970 lots.
Producers continued to add to their cover at the higher prices, adding 34k lots of shorts. End-users reduced their long position by 13.5k lots.
No.11 & No.5 Open interest
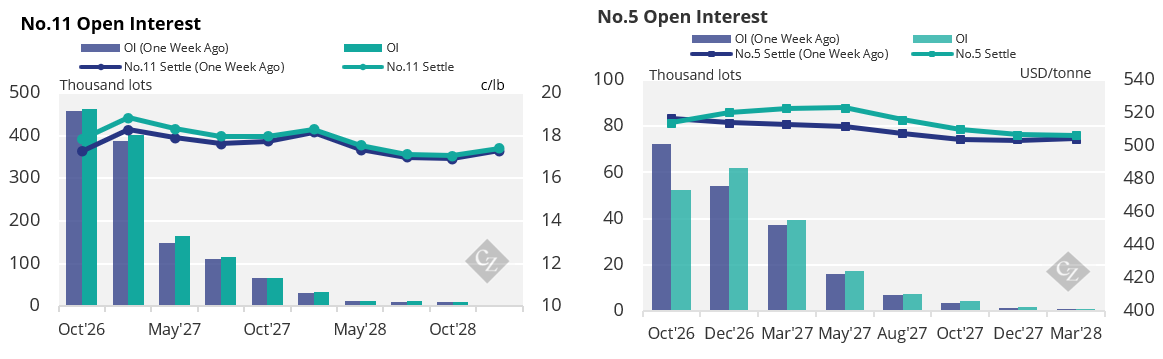
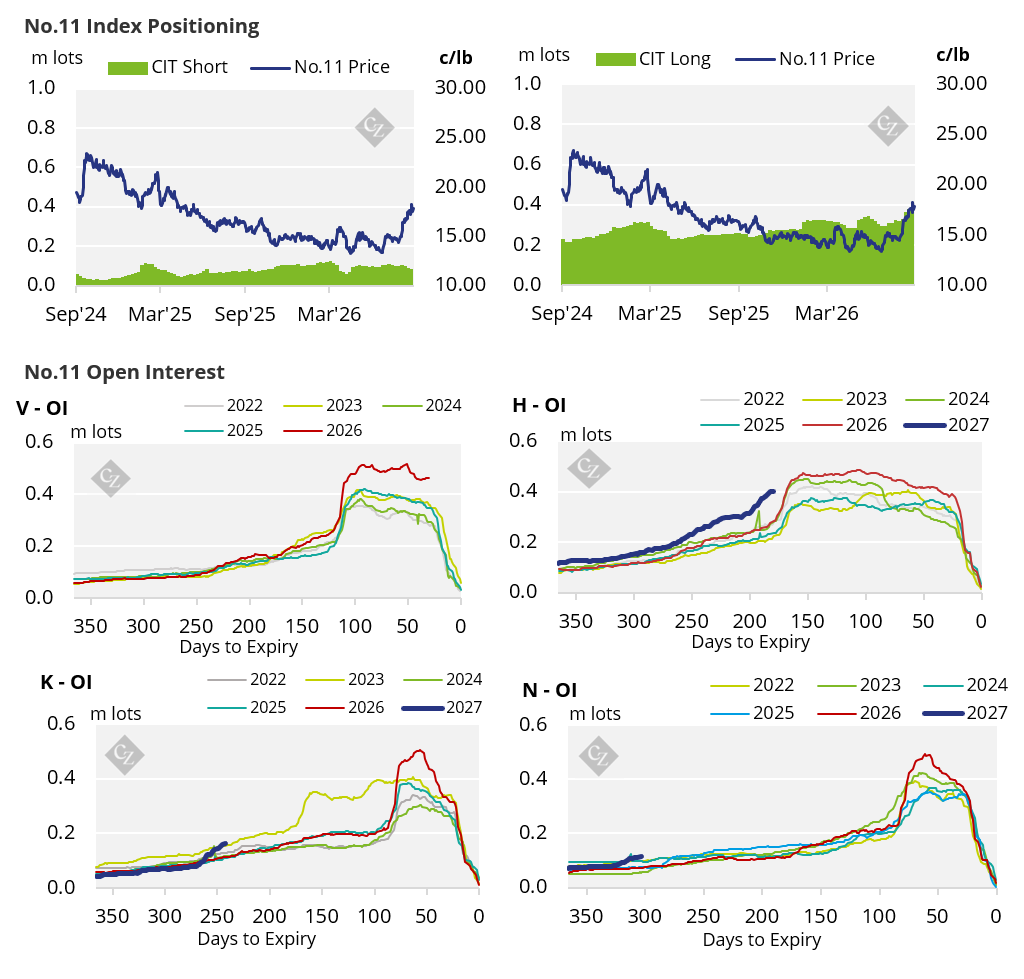
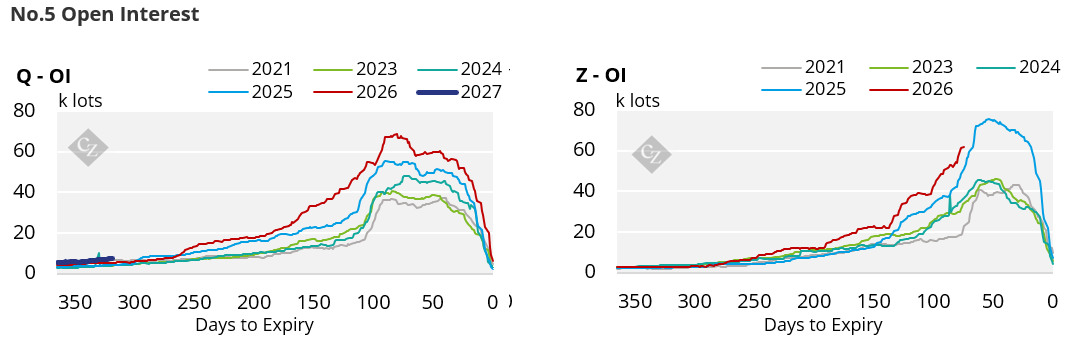
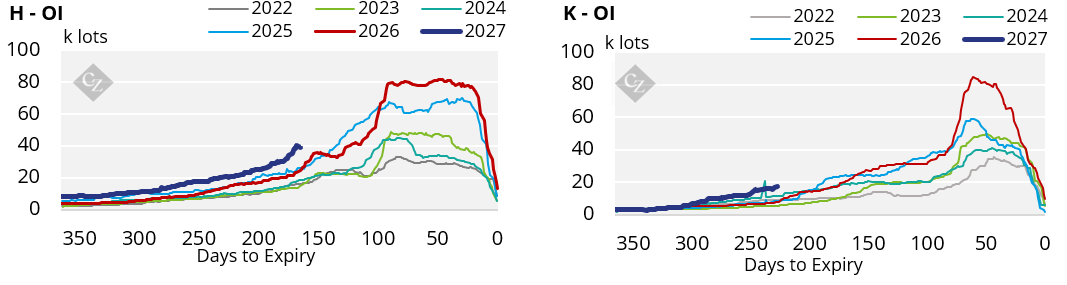
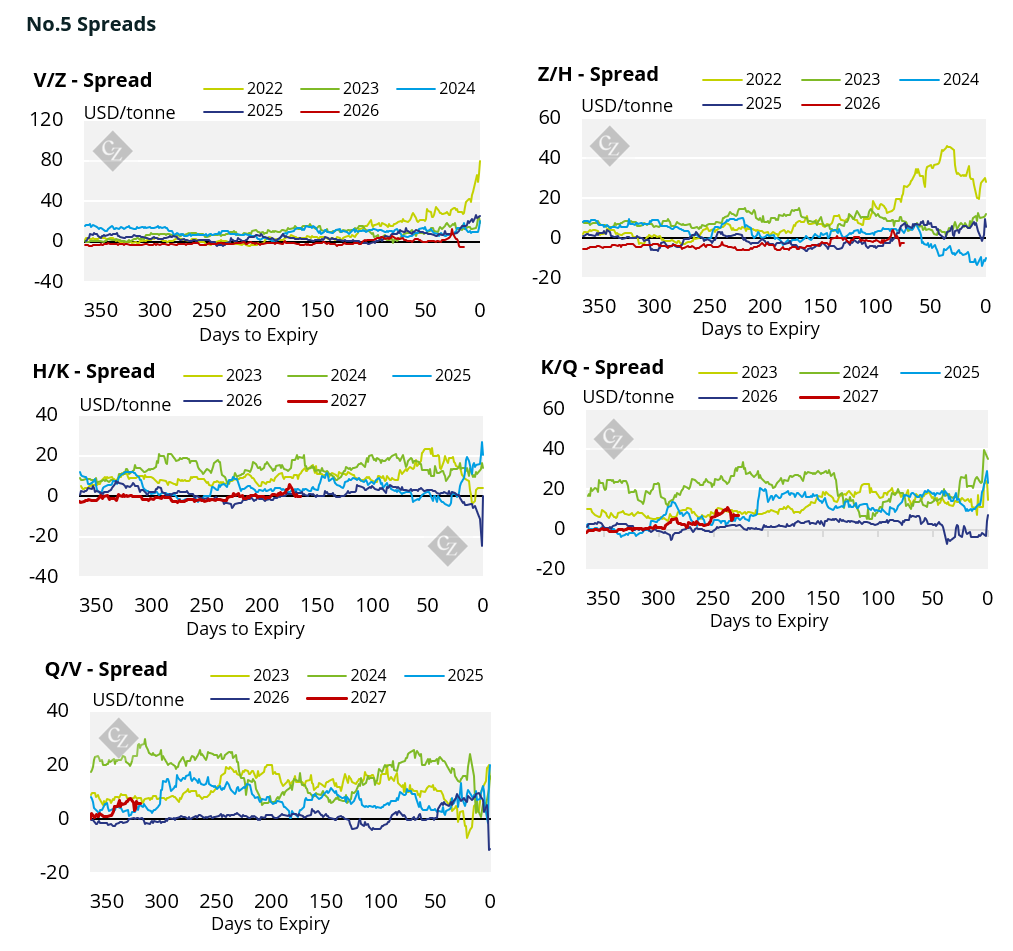
Open interest increased across most of the No.11 curve, with the largest additions in the March and May contracts. No.5 open interest moved out of the front contract and increased further along the curve.
White Premium (Arbitrage)
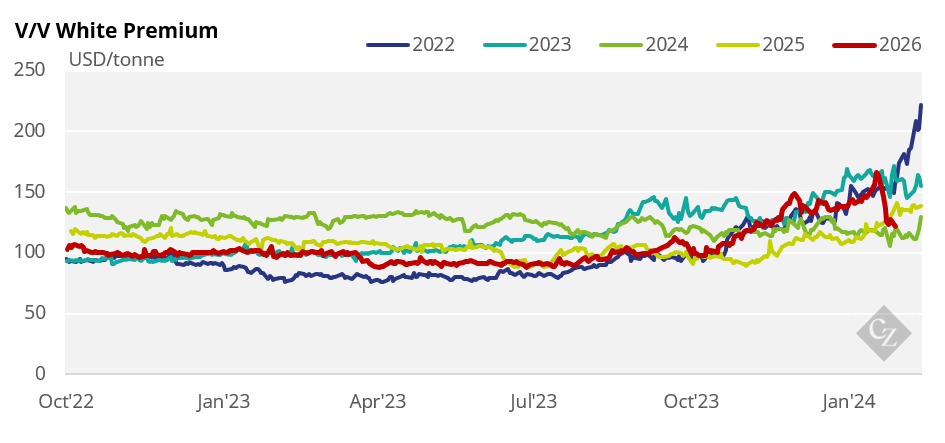
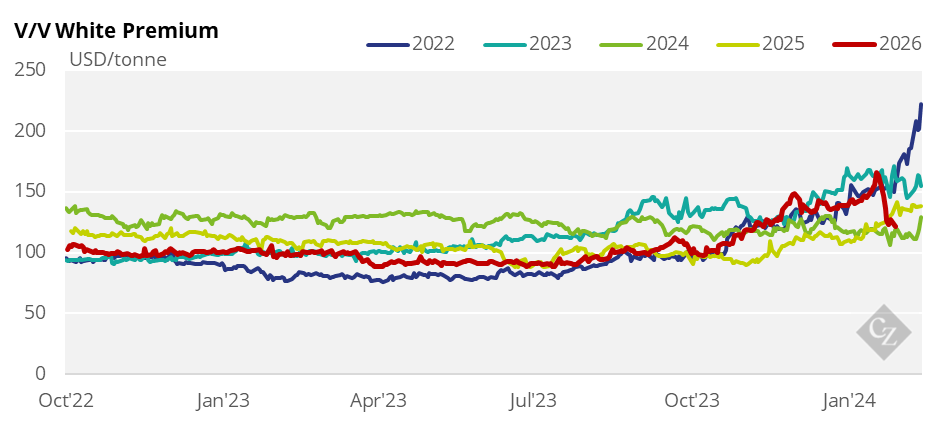
The V/V white premium fell from around USD136/tonne on Monday to USD122/tonne on Friday as No.11 strengthened relative to No.5.
Corn
Corn futures are trading around USD 512.5/bu, just below the recent three-year high of USD 515/bu reached on August 31 and are up roughly 15% over the past three months.
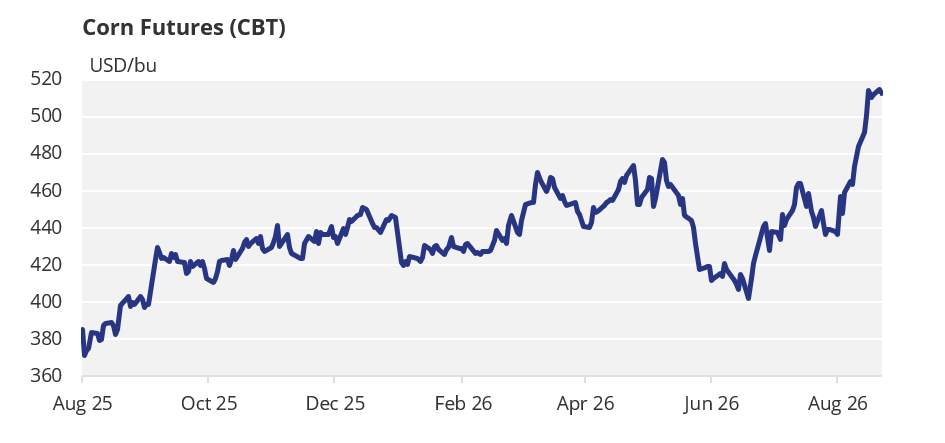
The rally has been driven primarily by concerns over lower US crop yields after the Pro Farmer Crop Tour reported weaker than expected production prospects across key growing regions, while the USDA is forecasting 2026/27 US ending stocks at 1.84 billion bushels, down 13.6% year on year, reflecting tighter supply expectations. Additional support has come from ongoing disruptions to Black Sea grain exports, which have added a geopolitical risk premium across agricultural commodities.
While larger crops in countries such as Brazil and Argentina may help offset some global supply concerns, overall grain stock forecasts continue to tighten and demand remains firm. Looking ahead, the market will be closely monitoring the next USDA WASDE report and late season US weather, but for now corn remains well supported near multi year highs as supply risks continue to outweigh bearish factors.
For a more detailed view of the sugar futures and market data, please refer to the appendix below.
No.11 (Raw Sugar) Appendix
No.5 (White Sugar) Appendix
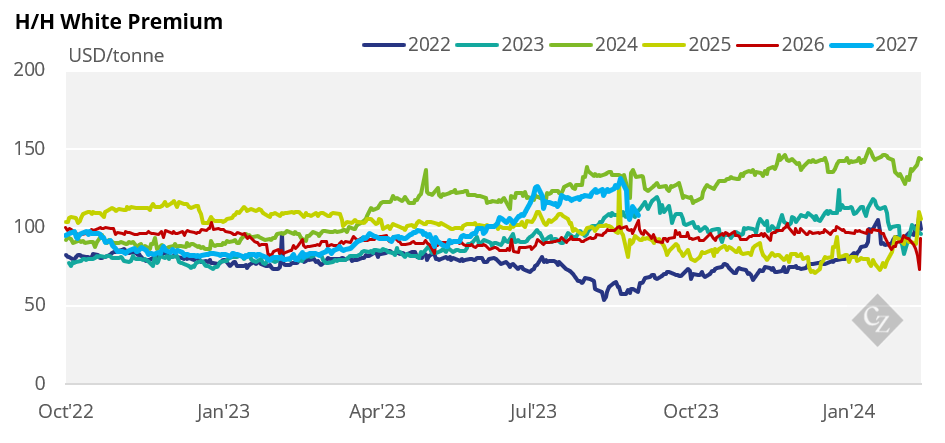
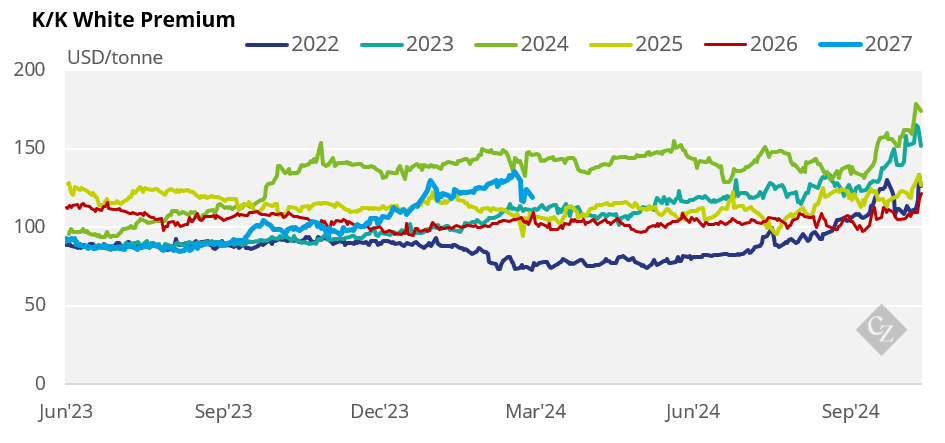
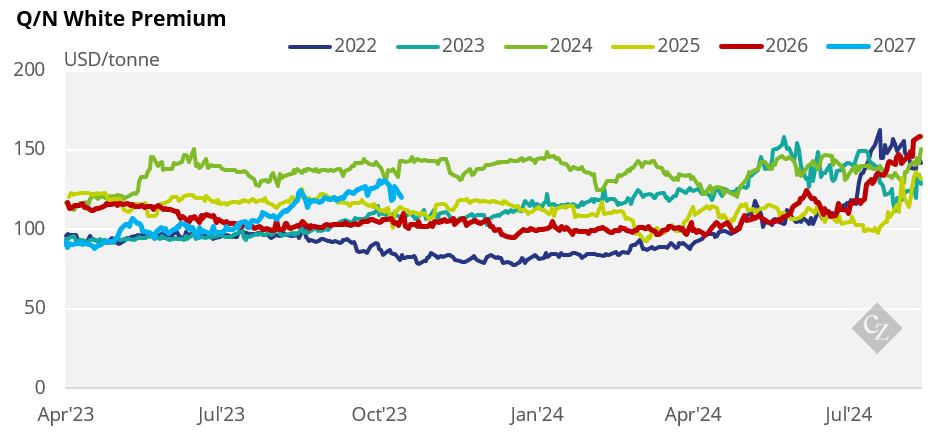
White Premium Appendix