Insight Focus
Black Sea disruption and lower US yields support grains. Corn has partially priced in the lower 173 bushels/year yield projected by the Pro Farmer tour, but further upside remains if the September WASDE confirms a smaller crop. Wheat should also remain supported unless Russia and Ukraine agree on an export corridor, with ongoing disruptions affecting a region responsible for nearly 30% of global wheat trade.
This update is from Nixal Commodities. For more information, CLICK HERE.
All grains rallied last week on continued supply disruptions out of the Black Sea and estimates of lower corn yields in the US.
Since our last report at the end of July, US corn condition has fallen from 67% to 60%, while France’s corn condition has plummeted to 29%, down from 38% just three weeks ago. Wheat exports out of Ukraine and Russia are also very low, as conflict continues. Inland routes through neighbouring countries could be used by Ukraine, but they are now at capacity with their own crops, and spare capacity is unlikely to be available until late Q4.
We think corn in Chicago has partially priced in the lower yield projected by the Pro Farmer tour, but there should still be significant upside if the September WASDE recognises that lower yield. A yield of 173 bushels/acre would require a sharp cut in exports to avoid critically low ending stocks, and that could be achieved through higher prices.
Wheat should also continue to have more upside than downside risk unless Russia and Ukraine agree on an export corridor. Otherwise, with the region responsible for almost 30% of global wheat trade, the situation can only be supportive for prices.
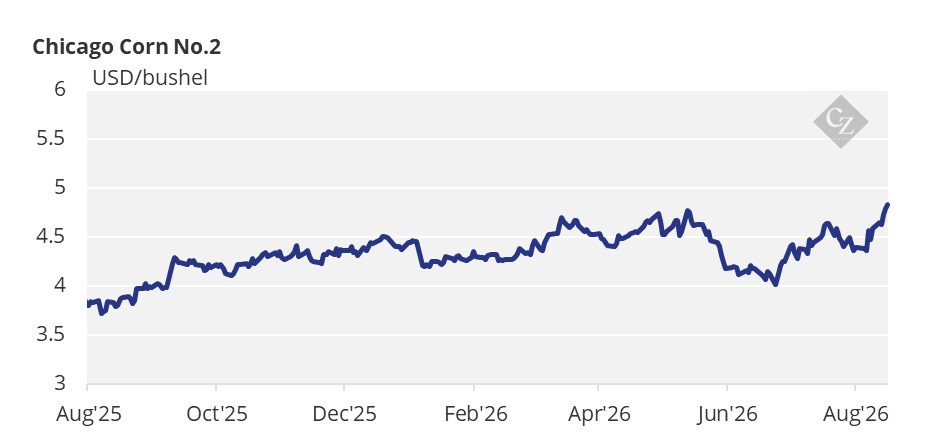
There are no changes to our forecast for Chicago corn, which we expect to average USD 4.4/bushel during the 2025/26 (September/August) crop year. The average price since September 1 is running at USD 4.37/bushel.
Corn Rally Fuelled by Yield Cuts and Flood Risks
Last Monday was a negative day for corn in Chicago, but as soon as the first results of the Pro Farmer tour were published, the market rallied through the end of the week after it projected a US corn yield of 173.2 bushels/year, well below the 180.7 bushels/year estimate in the August WASDE.
Before last week, the August WASDE was released, which reduced old-crop ending stocks by a significant 75 million bushels, entirely due to higher exports. However, the reduction in new-crop ending stocks was even larger at 137 million bushels, reflecting lower carry-in from the old crop, 13 million bushels of higher production (higher acreage but lower yield), and a 75 million bushel increase in exports. New-crop stock-to-use falls from 11% previously to 10.1% now.
World corn stocks were reduced by 600,000 tonnes. Russian production was increased by 1.4 million tonnes and Ukrainian production by 1.8 million tonnes, while EU production was reduced by 3.6 million tonnes (most likely all in France).
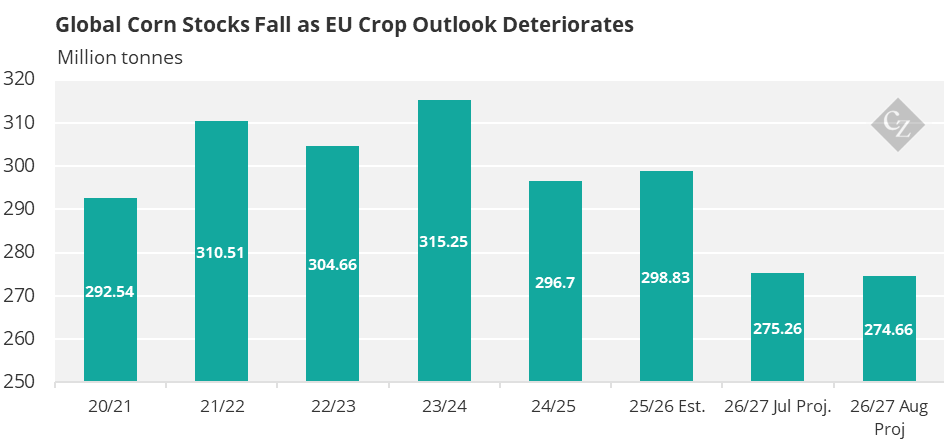
Source: USDA
However, the market was bulled up last week by yield tests from the Pro Farmer crop tour. On top of that, there was major flooding in parts of the eastern US Corn Belt, and damage to corn and soybeans is almost certain.
US corn condition is 60% good or excellent, down one percentage point week-on-week and versus 71% last year. Corn condition in France is 29% good or excellent, unchanged week-on-week and versus 62% last year. Summer corn harvesting in Brazil is now complete, in line with last year and the five-year average. Safrinha harvesting is 84.7% complete versus 89.3% last year and the five-year average of 86.6%.
Black Sea Tensions Continue to Underpin Wheat
The strength in corn spilled over into wheat, which also had its own bullish story as it continues to suffer from shipping disruptions out of the Black Sea.
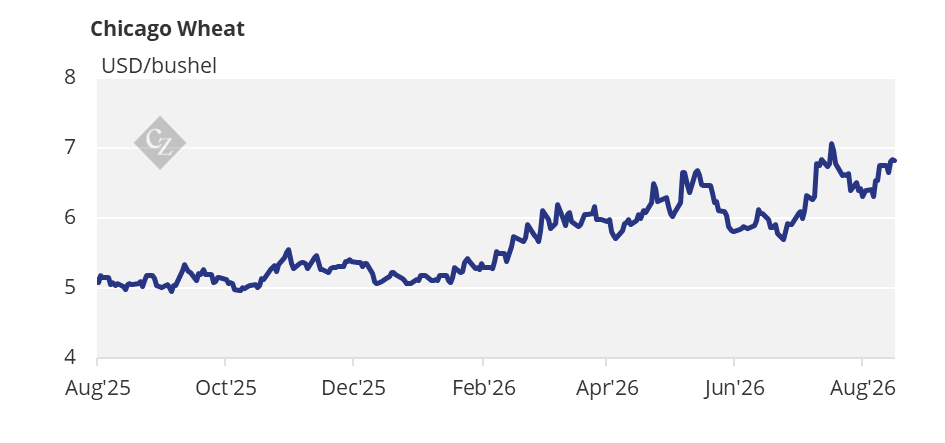
Exports from both Ukraine and Russia are facing serious challenges, as both countries continue to attack each other’s port infrastructure, and grain is leaving the region at a very slow pace. In fact, SovEcon reduced its August wheat export forecast for Russia to 2.2 million tonnes, compared with 4.5 million tonnes last year and the five-year average of 5 million tonnes. This was validated by weekly Russian wheat exports, which were down 62% week-on-week.
The August WASDE showed only immaterial changes to US ending stocks, which were reduced by just 5 million bushels, entirely due to a decline in yield from 47.9 bushels/acre to 47.8 bushels/acre.
World wheat stocks were increased by a marginal 410,000 tonnes, entirely due to higher beginning stocks. However, several changes were made to production estimates, including a 1 million tonne increase in Canada, a 1.8 million tonne reduction in the EU, a further 1.5 million tonne reduction in the UK, offset by a 1.4 million tonne increase in Ukraine and a further 1 million tonne increase in Kazakhstan.
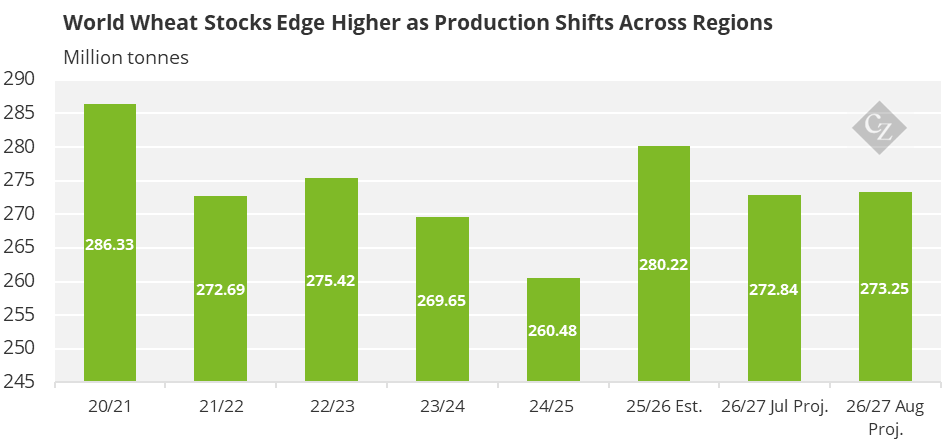
Source: USDA
US winter wheat is 96% harvested versus 93% last year and the five-year average of 94%. US spring wheat condition is 52% good or excellent, up one percentage point week-on-week and versus 50% last year. The spring wheat harvest is 41% complete, compared with 33% last year and the five-year average of 34%. The French wheat harvest is complete. Wheat harvesting in Russia is 66.3% complete versus 62% last year. Wheat harvesting in Ukraine is 94% complete. Wheat harvesting in Brazil is 4.7% complete versus 6.3% last year and the five-year average of 6.1%.
On the weather front, below-normal temperatures are expected in northwest Europe, along with rainfall that should help address soil moisture deficits across central and western regions, although the possibility of torrential rain raises flood risks. Dry conditions and cold temperatures are forecast in Brazil. In the US, normal temperatures and some rainfall are expected across the Corn Belt, which is favourable for corn development.