Insight Focus
The US sugar market maintains a firm tone on weather concerns. Weather-related production risks and limited 2027 selling opportunities kept US sugar supported, even as cash prices remained unchanged. Meanwhile, the USDA lowered its domestic production outlook for 2026-27 but raised import forecasts, particularly for Mexican sugar, helping to bolster supplies and improve stocks estimates from July levels.
This update is from Sosland Publishing’s Sweetener Report. For more information and subscription details, CLICK HERE.
Weather Risks Underpin Firm Sugar Market Tone
Activity in the cash sugar market was mixed this week. Prices were unchanged, but the market held a firm tone.
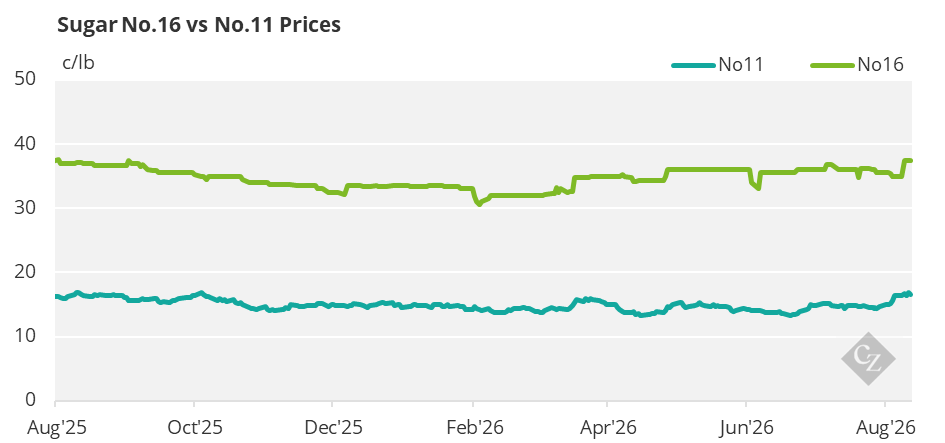
Users still needing to secure coverage for 2027 scrambled to find suppliers willing to sell, as concerns about this year’s crop led some to withdraw offers until they had a better handle on production. Other buyers were resigned to entering next season with only partial coverage, betting that prices may eventually decline or that market demand will naturally align with their expected inventories.
While the potential for tariffs had garnered most of the attention in the sugar market for much of the year, the spotlight has now shifted to domestic production. A barrage of weather extremes, beginning with spring freeze events and followed by heat and drought stress throughout the summer, has underpinned the market. Several processors have decided to defer harvest start dates, giving sugar beet crops a chance to receive rain before being lifted. The additional heat may enhance the crop by increasing sucrose content, but if conditions remain dry and growers continue to delay harvests while waiting for rain, the crop risks damage from an early freeze.
In addition to weather concerns, pest damage to sugar cane crops is now evident in both Louisiana and Florida, with the latter also still assessing damage and crop losses from a severe freeze event that occurred in late February.
USDA Raises Import Outlook as Domestic Production Weakens
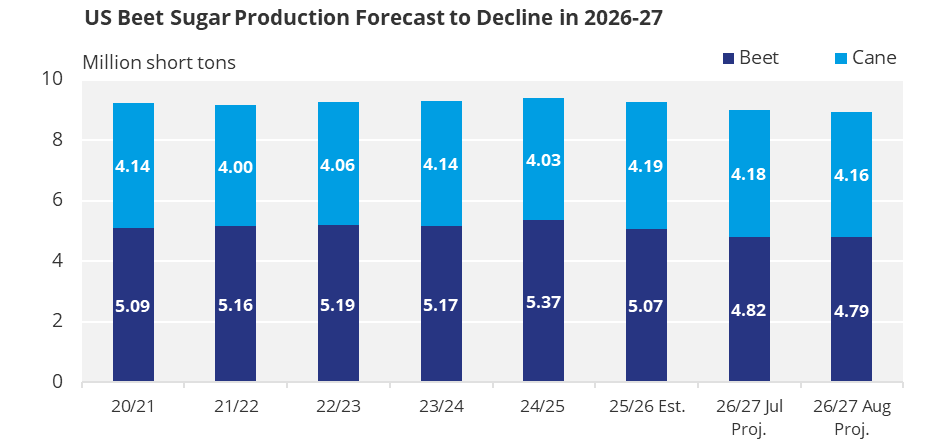
In the August 12 WASDE report, the USDA raised its 2025-26 beet sugar crop estimate to 5.068 million short tons (4.59 million tonnes), up 72,000 short tons from July but down 302,000 short tons, or 6%, from 2024-25. The Department projected 2026-27 beet production at 4.791 million short tons, down 0.6% from July, down 5% from the forecast for the current season, and the lowest level since 2019-20, if realised.
Cane sugar production for the current year was left unchanged from July at a record 4.189 million short tons, up 4% from 4.027 million short tons in 2024-25. The 2026-27 projection was reduced to 4.159 million short tons, down 0.6% from July and down 0.7% from 2025-26, but still the second-highest level on record, if realised.
Source: USDA
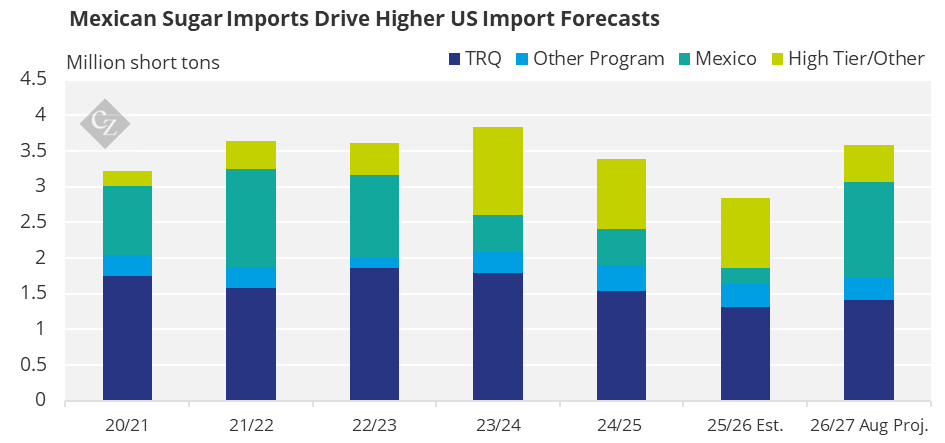
Sugar imports in 2025-26 were forecast at 2.843 million short tons, up 146,857 short tons from July but down 550,000 short tons from 2024-25. High-tier imports were forecast at 982,000 short tons, up 161,460 short tons from July.
For 2026-27, the USDA projected sugar imports at 3.582 million short tons, slightly higher than the 3.579 million short tons projected in July and 26% above the forecast for the current year. The increase largely reflected a sharp adjustment to imports of Mexican sugar, which were projected at 1.346 million short tons, unchanged from July but more than 500% higher than the 220,000 short tons forecast for the current year.
Source: USDA
Total supply for 2025-26 was forecast at 14.476 million short tons, up 219,000 short tons from July but down 455,000 short tons from 2024-25, while 2026-27 supply was projected at 14.436 million short tons, up 1.2% from July but down 0.3% from the current year.
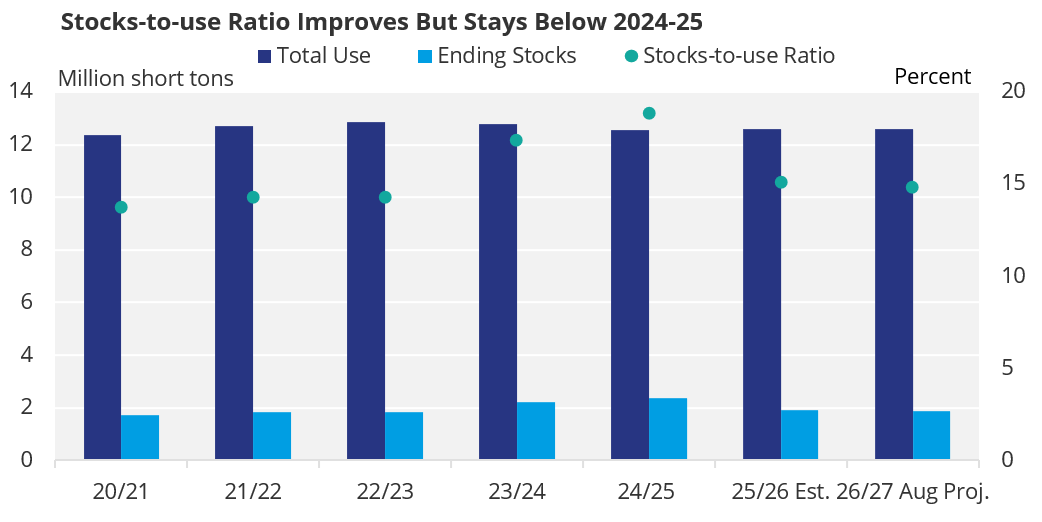
There were no changes from July in the 2025-26 sugar use forecasts, with food use projected at 12.441 million short tons. Ending stocks were forecast at 1.904 million short tons, up 218,000 short tons, or 13%, from July but down 472,000 short tons, or 20%, from 2024-25. The ending stocks-to-use ratio was forecast at 15.15%, up from 13.4% in July but down from 18.9% in 2024-25.
There were also no changes from July in the 2026-27 sugar use projections, with food use again forecast at 12.441 million short tons. Ending stocks were projected at 1.865 million short tons, up 10% from July but down 2% from the current season. The ending stocks-to-use ratio was projected at 14.8%, up from 13.5% in July but down from 15.1% in 2025-26.
Source: USDA
Corn sweetener market activity was routine, with negotiations starting for 2027 contracts.