Insight Focus
August saw conflict escalation, new sanctions and rising trade tensions. Black Sea attacks, expanded US sanctions on Iran and new US-Canada tariffs increased uncertainty across agricultural and commodity markets. Weather risks are also mounting, with forecasts pointing to a potentially historic El Niño that could disrupt crop production and support prices into 2027.
August Port Attacks Disrupt Black Sea Grain Flows
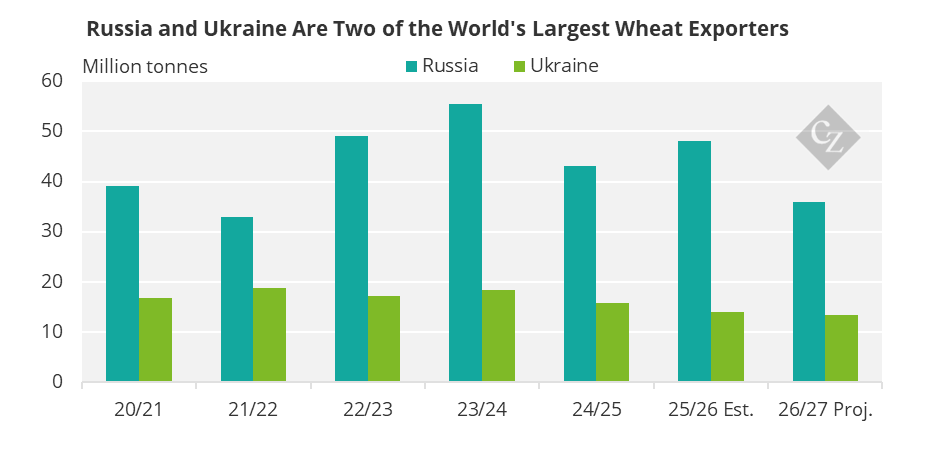
There was a sharp escalation in Black Sea attacks in August, with the grain trade facing its most significant disruption since Russia’s invasion of Ukraine in 2022. The most severe disruption came on 12 August, when Ukrainian strikes on Russia’s Novorossiysk export hub, combined with existing navigation restrictions in the Sea of Azov and the closure of the Taman terminal, left more than 90% of Russia’s grain export capacity in the Azov-Black Sea basin temporarily offline.
The disruption comes at a particularly sensitive time for global grain markets, as August to December is typically Russia’s busiest export period. Since attacks on Black Sea ports first intensified in July, wheat exports from both countries have fallen sharply, with SovEcon estimating Russian wheat exports are at their lowest level since 2010 and Ukrainian exports at their lowest level in sixteen years.
Source: USDA
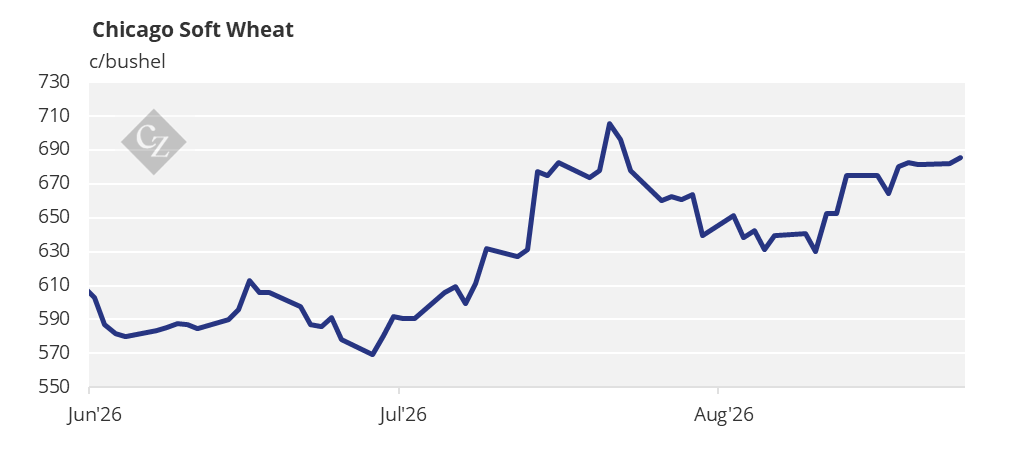
The disruption has already been reflected in wheat markets, with benchmark Chicago wheat futures rising more than 17% since early July as traders respond to reduced Black Sea supplies and growing uncertainty around export flows. Import-dependent regions are particularly exposed, with analysts warning that higher wheat prices, elevated freight costs and rising insurance premiums could increase food costs across Africa and other major wheat-importing regions that rely heavily on Black Sea supplies.
US Expands Iran Sanctions Campaign
Elsewhere, another conflict with significant implications for global commodity markets took a new turn on August 24, when the US launched an expanded sanctions campaign aimed at further isolating Iran from the global economy.
The US Treasury imposed sanctions on nearly 60 individuals, companies and vessels linked to Iranian oil sales, military procurement and cyberoperations, while also warning countries, banks and businesses that continued dealings with Tehran could face broader secondary sanctions in the future. US Treasury Secretary Scott Bessent described the measures as an “economic onslaught”.
The sanctions target entities operating across China, Hong Kong, Singapore, the UAE and Europe, including firms involved in shipping, commodity trading, logistics and trade finance that Washington alleges have helped facilitate Iranian oil exports, technology procurement and sanctions evasion.
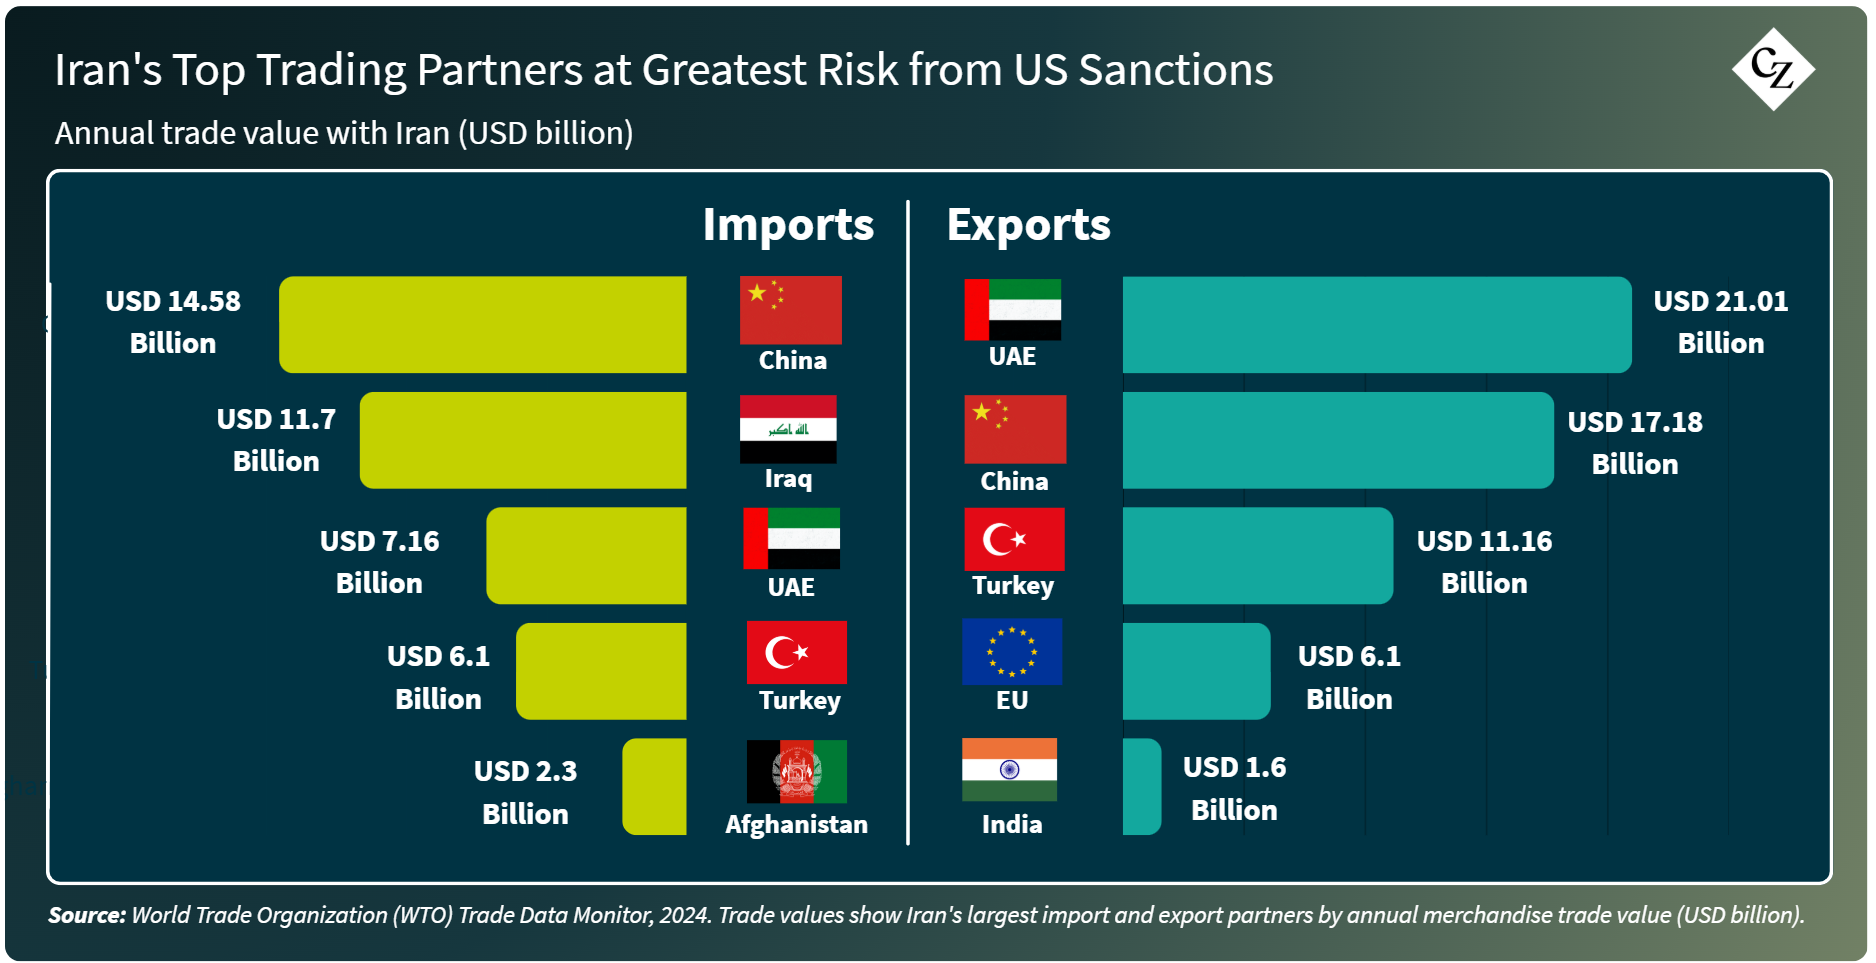
The greatest uncertainty surrounds China, Iran’s largest oil customer. More than 80% of Iran’s seaborne oil exports have historically been destined for China, with Kpler estimating Chinese purchases averaged 1.38 million barrels per day in 2025, although imports have fallen sharply during the conflict.
Beijing has already pushed back against the latest measures, stating it is firmly opposed to what it called “illegal unilateral sanctions” and warning it would take “all necessary measures” to protect its interests. While Washington stopped short of sanctioning major Chinese financial institutions, Treasury officials made clear that no country is beyond the reach of future sanctions, setting up a potential point of tension ahead of planned talks between Presidents Trump and Xi next month.
The sanctions come as shipping through the Strait of Hormuz remains heavily disrupted. Lloyd’s List Intelligence recorded 73 vessel transits between 10 and 16 August, down from 91 the previous week, while container throughput at Dubai’s Jebel Ali port remains around 10% of normal levels as cargo is rerouted through Fujairah, Khor Fakkan, Oman and Saudi Arabia. Freight markets have responded accordingly, with tanker rates on key Middle East export routes surging as shipowners demand higher premiums to operate in the region.
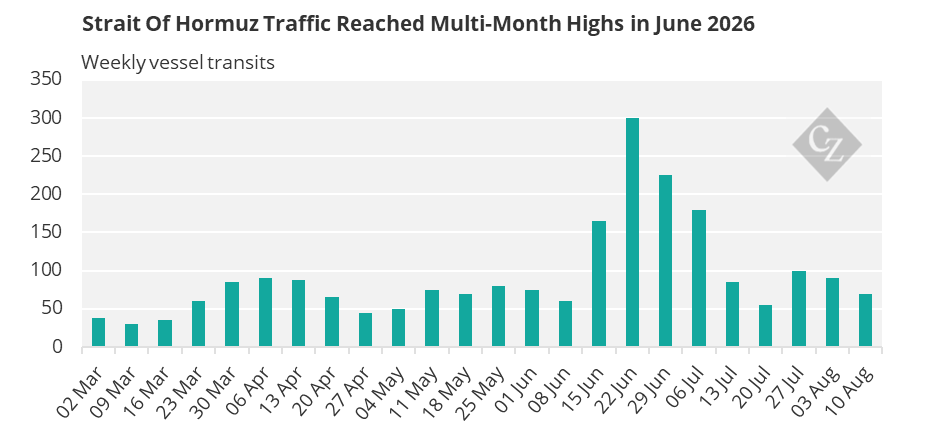
Source: Lloyd’s List Intelligence
The implications extend beyond energy markets. On August 24, the United Nations proposed a mechanism to facilitate fertiliser shipments through the Strait of Hormuz, highlighting growing concerns over the movement of key agricultural inputs
US and Canada Escalate Trade Dispute with New Tariffs
At the same time, the US is also facing a trade breakdown with Canada, one of its closest economic partners. After negotiations failed to produce an agreement by President Trump’s August 21 deadline, Washington imposed 50% tariffs on approximately USD 28 billion of Canadian goods. Ottawa responded by pledging a dollar-for-dollar response, announcing retaliatory tariffs on nearly CAD 28 billion of US products that are due to take effect on September 8.
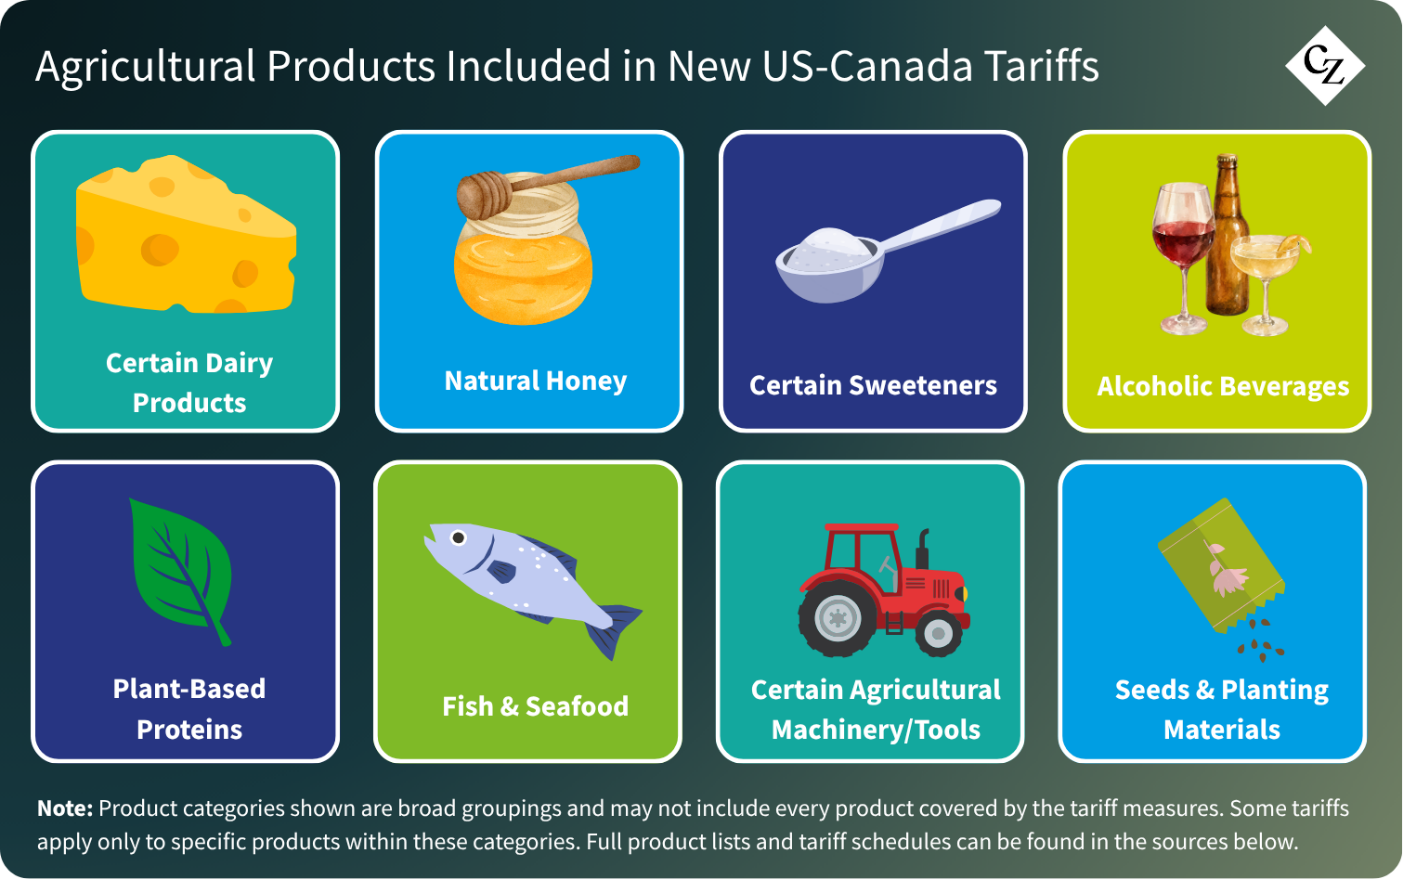
For agriculture, the measures are targeted rather than broad-based. The US tariffs exclude most major agricultural commodities but apply to several higher-value products and inputs, including dairy products, alcohol, sugars, honey, plant-based proteins and agricultural machinery.
Canada’s response is more varied, including 50% tariffs on natural honey and 25% tariffs on dairy products such as cheese, alongside duties on fish and seafood, appliances and industrial goods. Certain tools and machinery will also face 15% tariffs.
Sources: Government of Canada, White House
The inclusion of agricultural machinery on both countries’ tariff lists could increase equipment costs for producers, while tariffs on dairy products, sweeteners, honey and plant-based proteins are likely to raise costs for processors and food manufacturers operating across the US-Canada border. The dispute also casts uncertainty over the future of the USMCA framework, which underpins trade across one of the world’s most integrated agricultural markets.
Markets Brace for a Potentially Record-Breaking El Niño
Weather has also re-emerged as a major concern for agricultural markets, with forecasts increasingly pointing towards a potentially historic El Niño event developing through late 2026 and into 2027. NOAA’s August outlook assigns a greater than 90% probability of a very strong El Niño, with a 69% chance that conditions between October and December exceed the strength of every El Niño event recorded since 1950. Forecasts indicate the event is likely to continue intensifying through the autumn before peaking between October and January.
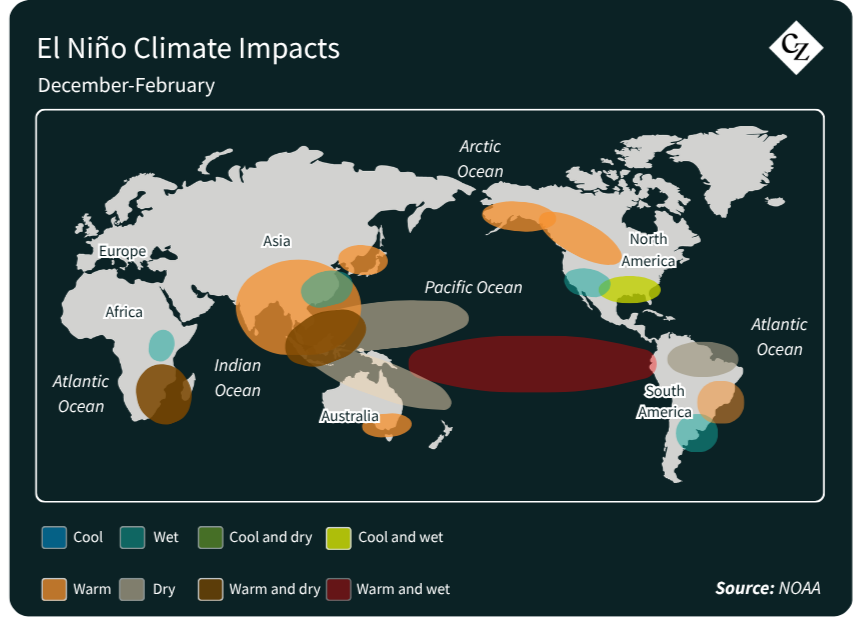
Unlike geopolitical disruptions, El Niño does not create a uniform global shock. Instead, risks are highly regional, with analysts highlighting dryness risks for soybeans and second-crop corn in Brazil, weaker monsoon conditions in India, dryness across Southeast Asia that could affect palm oil production and hotter, drier conditions for Australian wheat and barley. Argentina could experience the opposite problem, with wetter conditions potentially disrupting fieldwork and increasing flood risk.
Financial markets are beginning to reflect these concerns. Citi recently raised its three-month corn, soybean and wheat price forecasts to USD 5.40/bushel, USD 12.75/bushel and USD 7.25/bushel respectively, identifying a strengthening “Super El Niño” as its highest-conviction agricultural risk heading into late 2026 and early 2027.
The bank highlighted palm oil, robusta coffee, rice, sugar, cocoa and Australian wheat among the commodities most exposed to weather-related disruption, while warning that markets may not yet fully reflect the potential production risks associated with an exceptionally strong event.