Insight Focus
The US sugar beet harvest accelerated as frost risks emerged. Growers increased harvest activity to protect crop quality, although warmer weather forecasts in some regions may still allow fieldwork to continue for longer. Cash sugar prices remained firm as supply uncertainty persisted and several sellers continued to withhold 2027 offers.
This update is from Sosland Publishing’s Sweetener Report. For more information and subscription details, CLICK HERE.
Sugar Beet Harvest Accelerates Ahead of Frost Risk
Attention in the cash sugar market remained focused on the new crop this week, as traders worked to better assess production prospects and supply availability. Prices were steady but firm, and several sellers continued to withhold 2027 offers.
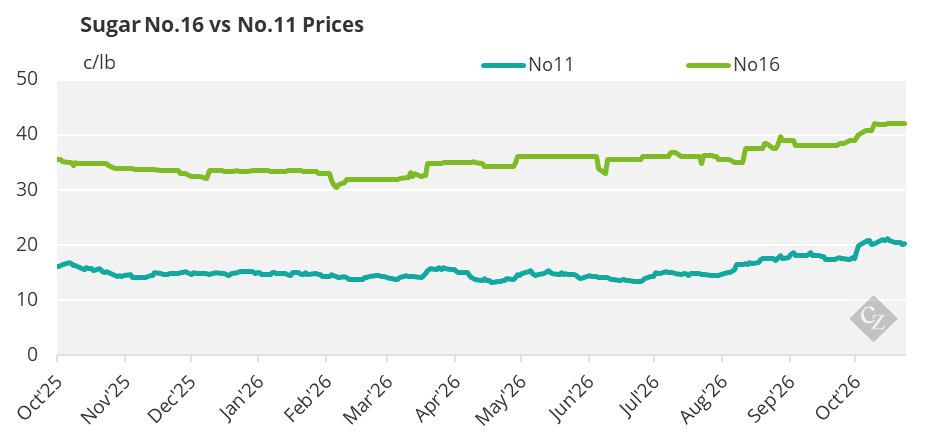
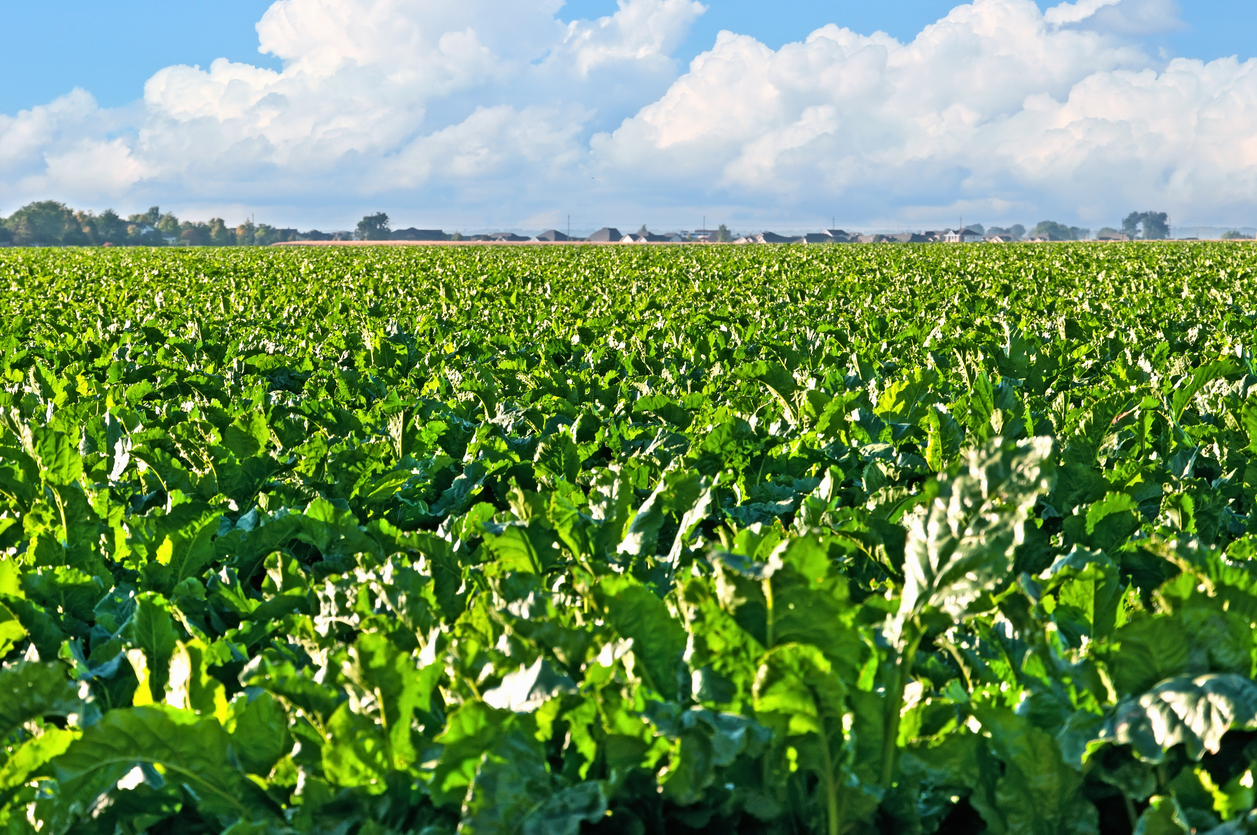
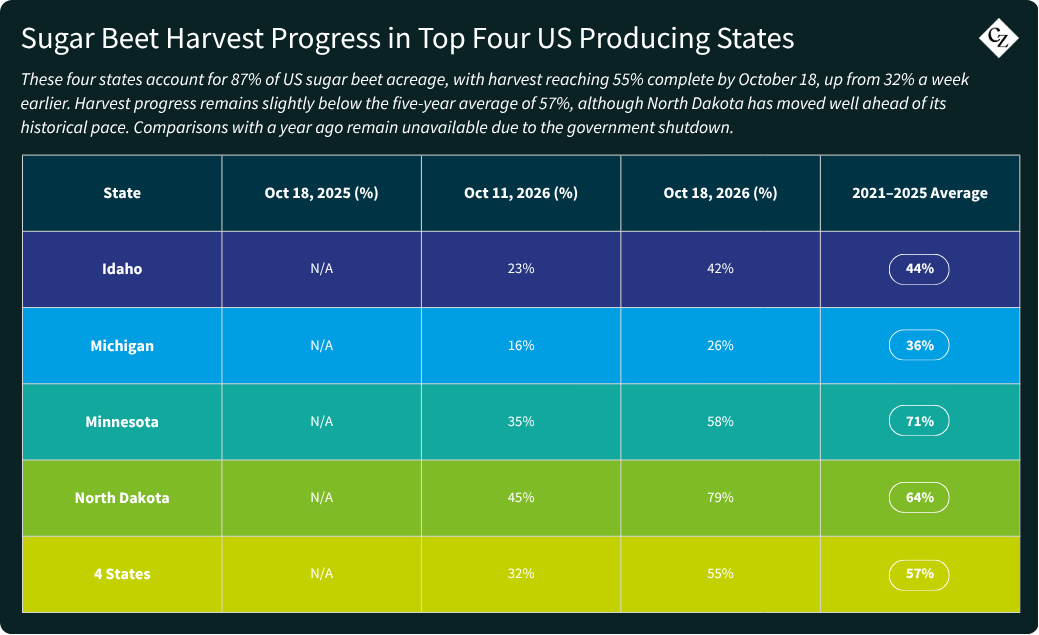
Harvest of the domestic sugar beet crop accelerated, bringing collection rates closer to five-year average levels. Growers had been delaying harvest in the hope that late-season moisture would boost root development and sugar content. However, with freeze and frost threats beginning to emerge in weather forecasts, the focus shifted toward protecting the crop from quality losses, making timely harvest a higher priority than waiting for additional sugar accumulation.
The USDA reported harvest completion as of October 18 at 58% in Minnesota (35% a week earlier, 71% five-year average), 79% in North Dakota (45%, 64%), 42% in Idaho (23%, 44%), 26% in Michigan (16%, 36%), 55% in Colorado (29%, 62%) and 58% in Wyoming (40%, 68%). The sugar cane harvest in Louisiana was 22% complete as of October 18, ahead of the average pace of 20%.
Source: USDA
Still, not all growers felt a sense of urgency. The National Oceanic and Atmospheric Administration’s 8-to-14-day outlook indicated that above-normal temperatures were likely to persist across several major sugar beet-producing regions, including Colorado, Michigan and parts of Minnesota, potentially extending the window for fieldwork before freeze threats become widespread.
“We’re going to keep the crop growing as long as we can,” one processor said. “We’re not permanent piling yet. We’re just pulling and feeding factories because the warmer weather allows the crop to keep growing. We may not start permanent piling until late October.”
Buyer Interest Persists Amid Supply Questions
The uneven sugar beet harvest continued to bolster cash market sentiment, keeping prices firmly supported. Lingering concerns over delayed harvest progress and potential crop quality issues fostered expectations of tighter supplies, helping the domestic sugar market stand apart from many other agricultural commodities that have been under pressure.
The uncertainty also sustained buyer interest. Although most large end users secured a significant portion of their 2027 needs several months earlier, one processor estimated that about 20% of users still remained uncovered.
“We have a lot of people calling us and looking for extra loads,” one supplier said. However, sources indicated the increase in inquiries may reflect logistical constraints rather than strengthening demand.
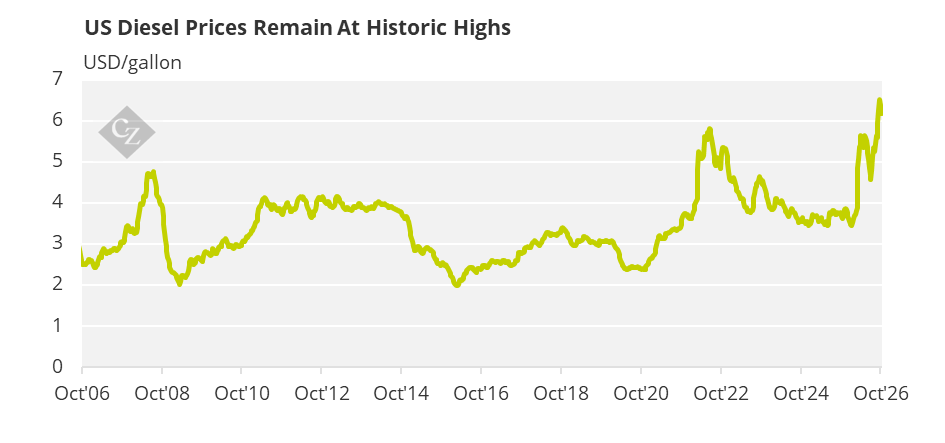
Elevated diesel costs have likely shortened economical delivery distances, and many of the requests have been for relatively small quantities, suggesting buyers may only be seeking nearby supply.
Source: EIA
Negotiations for annual corn sweetener contracts continued to drag on as corn prices remained under pressure, giving buyers additional leverage to push for lower pricing. While large-volume users have been able to roll 2026 pricing into their 2027 contracts, roughly half of outstanding agreements, primarily involving mid-sized and smaller users, have yet to be finalised.