Insight Focus
We forecast that the world will produce 0.9m tonnes less sugar than it consumes in 2026/27, following a reduction to our CS Brazil production forecast. This shortfall could grow to 2.9m tonnes in 2027/28 as lower cane and beet availability reduces production in India, the EU and Thailand.
2027/28 at a Glance…

All figures in m tonnes tel quel
We forecast global sugar production at 177m tonnes in 2027/28, down by 1.3m tonnes from 2026/27. With consumption broadly stable at 179.9m tonnes, we forecast a global sugar deficit of 2.9m tonnes.
Lower Crop Area Tightens the 2027/28 Outlook
Our first 2027/28 outlook points to lower global sugar production, led by declines in India, the EU and Thailand. We think cane and beet area could fall in each of these markets.
We forecast India’s sugar production to fall to 26-27m tonnes in 2027/28, as poor monsoon conditions could reduce cane planting in parts of Maharashtra and Karnataka. A greater reliance on older ratoon cane could also reduce yields in Maharashtra. Our latest estimate for Indian sugar production in 2026/27 is 28.4m tonnes; however there could be some upside to this if high domestic sugar prices reduce diversion of sucrose to ethanol.
We are tentatively projecting the EU will make 13.2m tonnes of sugar in 2027/28. Continued pressure on grower and processor profitability could lead to a further reduction in beet area, we expect yields to remain around average levels. This compares to 13.9 we currently project for 2026/27. There is however a growing downside risk to this as Europe continues to suffer from extreme heat and drought.
In Thailand competitive cassava returns could encourage farmers to switch crops when older ratoon cane needs replacing. This could reduce the cane crush from around 95m tonnes in 2026/27 to 80-90m tonnes. Assuming an average sugar recovery rate of 11%, this would result in sugar production of 9.3m tonnes in 2027/28.
Global Sugar Production
Since last month, we have reduced our 2026/27 global sugar production forecast by 0.2m tonnes to 178.3m tonnes. A 0.9m-tonne reduction in Centre-South Brazil more than offsets higher forecasts for China, Pakistan, Indonesia and the US.
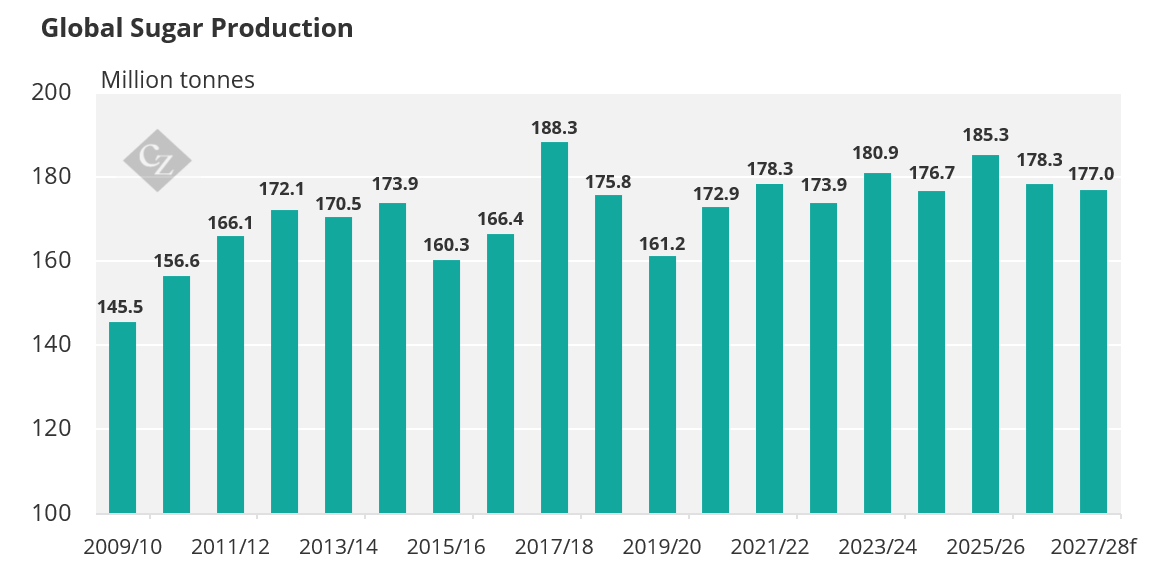
We have reduced our CS Brazil production forecast by 0.9m tonnes to 38.6m tonnes. Heavy rainfall in June and July lowered cane sugar content, while we have also reduced our cane crush and sugar-mix assumptions. The recent recovery in sugar prices has supported mills’ sugar returns, preventing a larger reduction in the sugar mix.
Higher production forecasts elsewhere partially offset the reduction in Brazil. We’ve increased China’s production forecast by 0.3m tonnes, reflecting expectations of improved yields. We’ve also raised Pakistan’s production forecast by 0.4m tonnes following a stronger previous crop. We have increased our production forecasts for Indonesia and the United States by 0.2m tonnes each, while in Russia we have reduced production by 0.2m tonnes.
Global Sugar Consumption
We now forecast global sugar consumption at 179.2m tonnes in 2026/27 and 179.9m tonnes in 2027/28. We have slightly increased our consumption forecast this month after reviewing the USDA’s historical revisions to US demand estimates, which account for previous underreporting. We have raised our US consumption forecast to reflect this new information.
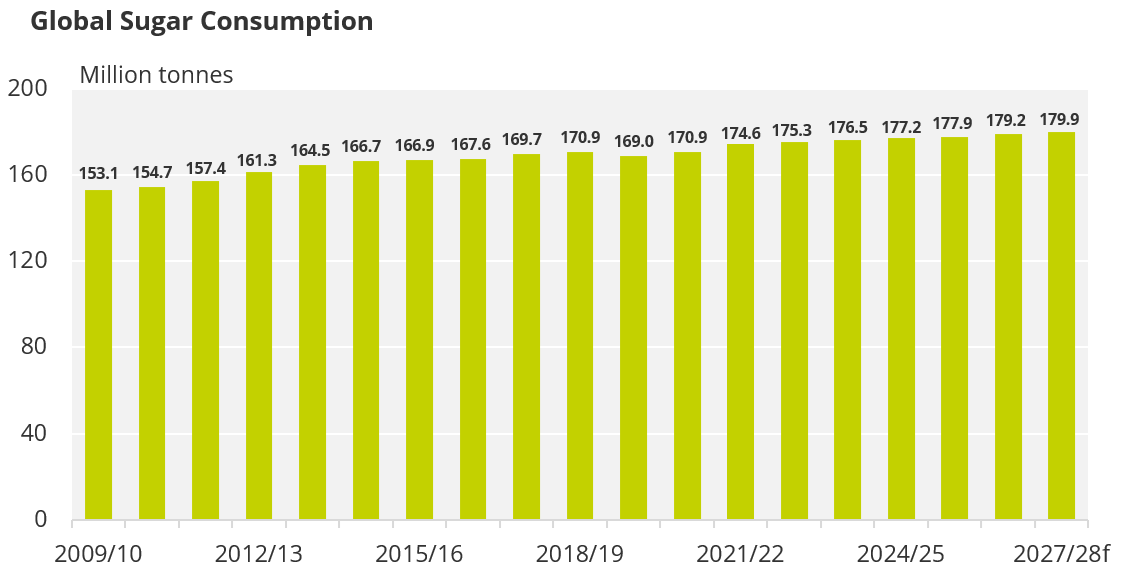
Global sugar consumption growth nevertheless remains modest. High food prices, product reformulation, health awareness and the GLP-1 story continuing to limit upside in some markets.
The Global Sugar Deficit Increases
The gap between global sugar production and consumption has widened from 0.6m tonnes to 0.9m tonnes since last month. A reduction in our CS Brazil production forecast more than offsets higher forecasts elsewhere, while we have also slightly increased expected consumption.
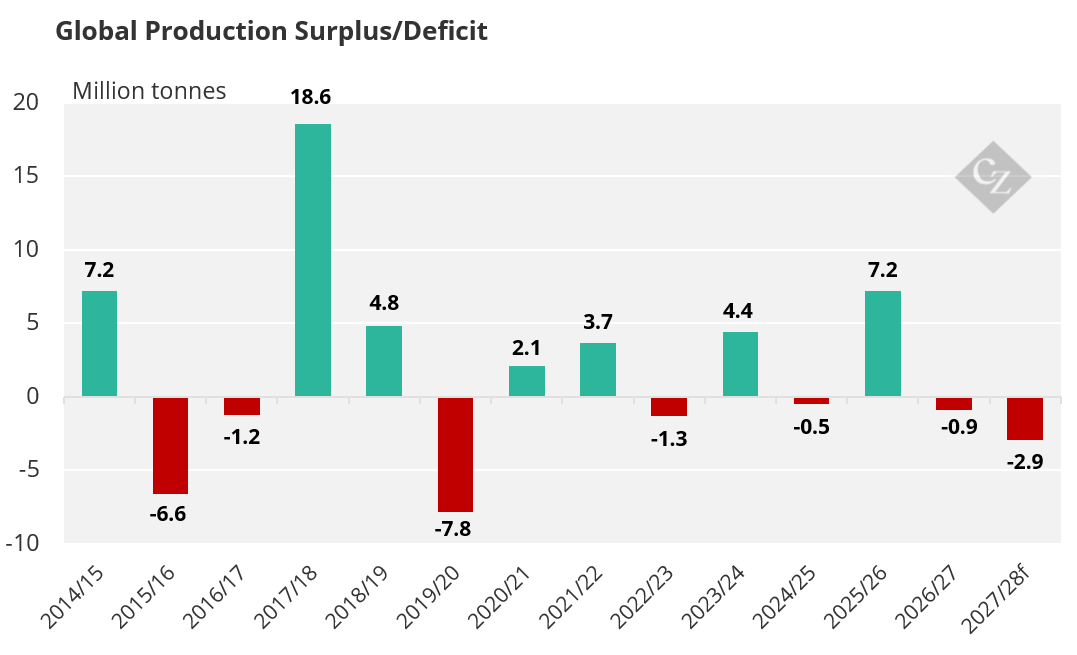
We expect the deficit to deepen further in 2027/28. We forecast production to fall by 1.3m tonnes to 177m tonnes, while consumption rises by 0.7m tonnes to 179.9m tonnes, widening the deficit to 2.9m tonnes.
Stocks built during the large 2025/26 surplus should provide some protection. However, deficits in consecutive seasons would reduce that buffer and leave the market more exposed to adverse weather or further production downgrades.
Other Sugar Producers at a Glance…
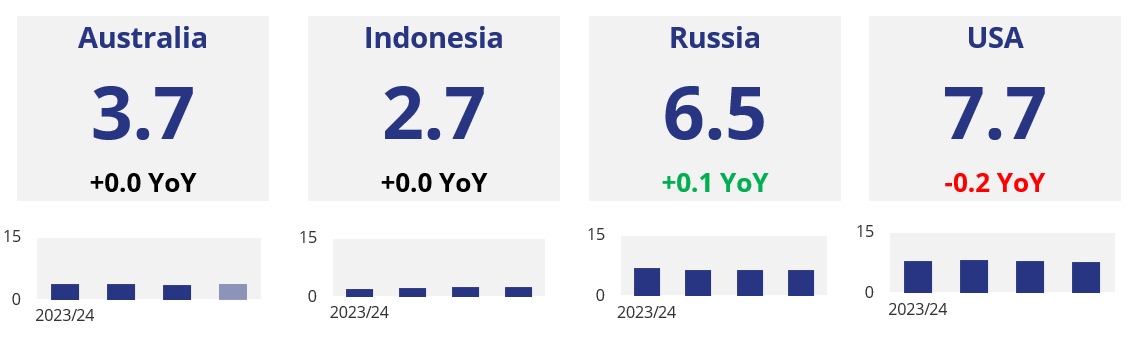
All figures in m tonnes tel quel