Insight Focus
Tighter US sugar supplies continue to support domestic prices. USDA lowered its 2026-27 production and overall supply forecasts, while stocks-to-use are expected to fall to 13.9%. Imports are forecast higher, but buyers remain cautious amid elevated domestic prices.
This update is from Sosland Publishing’s Sweetener Report. For more information and subscription details, CLICK HERE.
US Sugar Production Outlook Tightens
The latest USDA supply-and-demand report validated expectations for tighter sugar supplies, leaving prices unchanged but well supported this week. Trading activity remained stalled, as most users shied away from high domestic prices. Some buyers needing fill-in coverage sought lower-priced offers from foreign suppliers.
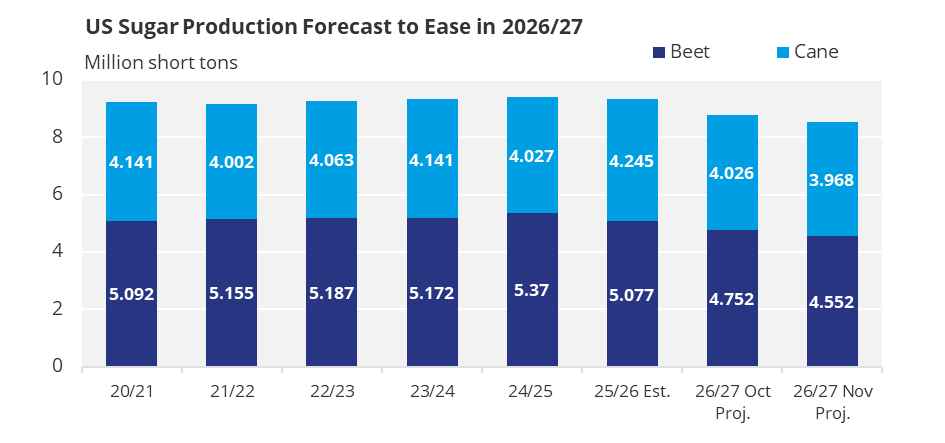
In the November 10 WASDE report, the USDA forecast US sugar production in 2026-27 at 8.5 million short tons (7.73 million tonnes), down 248,000 short tons, or 2.8%, from October and down 802,000 short tons, or 9%, from the 9.32 million short tons estimated in 2025-26.
The lower outlook was driven primarily by a reduction in beet sugar production, forecast at 4.55 million short tons, down 190,000 short tons, or 4%, from October and down 525,000 short tons, or 10%, from 2025-26.
The USDA also trimmed its forecast for 2026-27 cane sugar production to 3.97 million short tons, down 58,000 short tons, or 1.4%, from October and down 277,000 short tons, or 7%, from 2025-26.
Source: USDA
According to the Department’s Crop Production report, also released November 10, sugar beet output was expected to decline year over year in nine of the nation’s 10 sugar beet-producing states, reflecting reductions in both harvested acreage and yields. Year-over-year sugar cane production also was lower, due largely to the impacts of the pasture mealy bug on both the Louisiana and Florida crops.
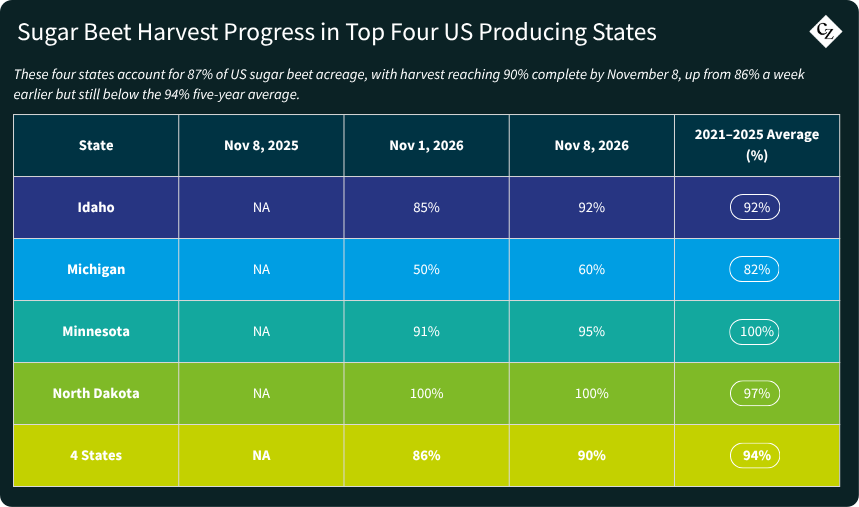
As of November 8, about 90% of the domestic sugar beet crop had been harvested, with 95% of the crop collected in Minnesota (versus 91% a week earlier and 100% as the five-year average), 100% in North Dakota (100%, 97%), 92% in Idaho (85%, 92%), 60% in Michigan (50%, 82%), 95% in Colorado (89%, NA) and 95% in Wyoming (85%, 95%). By the same date, 46% of the sugar cane crop had been harvested in Louisiana, compared with 40% a week earlier and 39% as the 2021-25 average for the date.
Source: USDA
US Sugar Supplies Tighten Despite Higher Imports
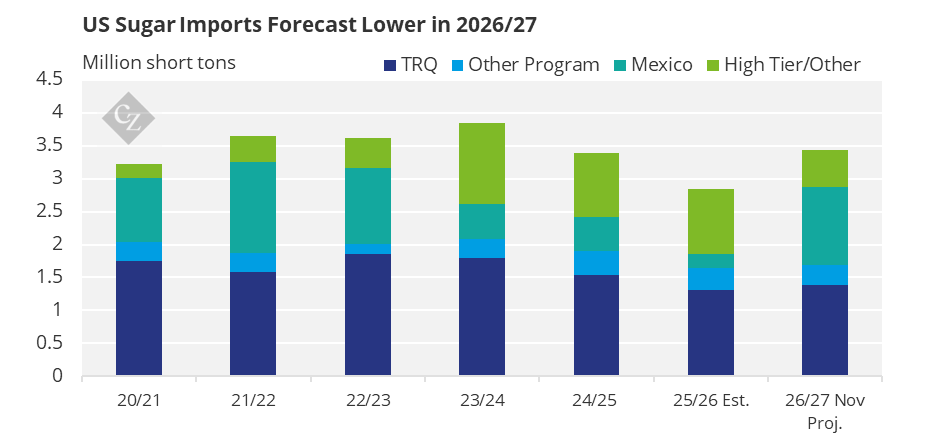
The USDA forecast total US sugar supply for 2026-27 at 14.15 million short tons, down 1.7% from October and down 4.1% from the 14.76 million short tons estimated in 2025-26. Total imports for 2026-27 were raised to 3.43 million short tons, up 12% from last season, reflecting increased year-over-year volumes from tariff-rate quota, non-program and Mexican supplies.
Source: USDA
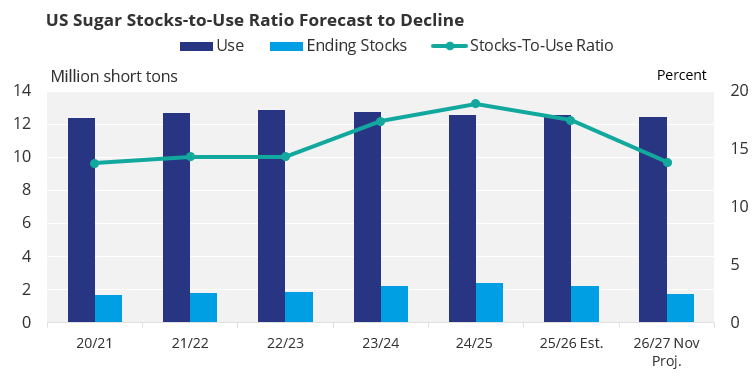
In the November WASDE, the USDA forecast 2026-27 food deliveries at 12.3 million short tons, down 0.8% from the prior month’s outlook. The stocks-to-use outlook was lowered to 13.9%, down from 14.9% in October and from the 17.5% estimated in 2025-26.
Source: USDA
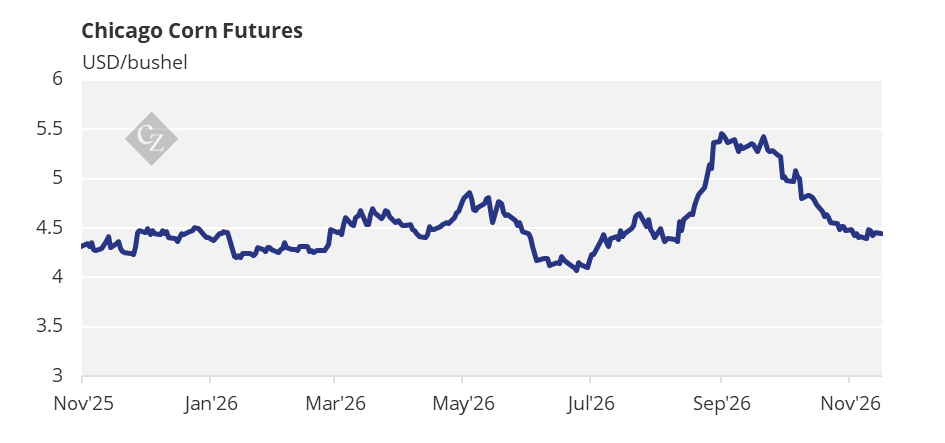
The rebound in corn futures injected new life into the corn sweetener market. Buyers who had used the extended decline in corn prices to push back against higher offers remained cautious, however, with most taking a wait-and-see approach before making commitments.