Insight Focus
Tight supplies are keeping US sugar prices firm. Buyers are delaying purchases amid high prices, while sellers remain cautious as uncertainty over crop prospects and surplus availability persists. The sugar beet harvest is nearing completion, but wet weather, Florida cane supply concerns and policy uncertainty continue to cloud the market outlook.
This update is from Sosland Publishing’s Sweetener Report. For more information and subscription details, CLICK HERE.
Tight Supplies Keep US Sugar Market Firm
The domestic cash sugar market remained firm this week amid an outlook for tight supplies and steady demand. Prices for spot and 2027 US cane sugar supplies were unchanged, but values for domestic beet sugar moved higher.
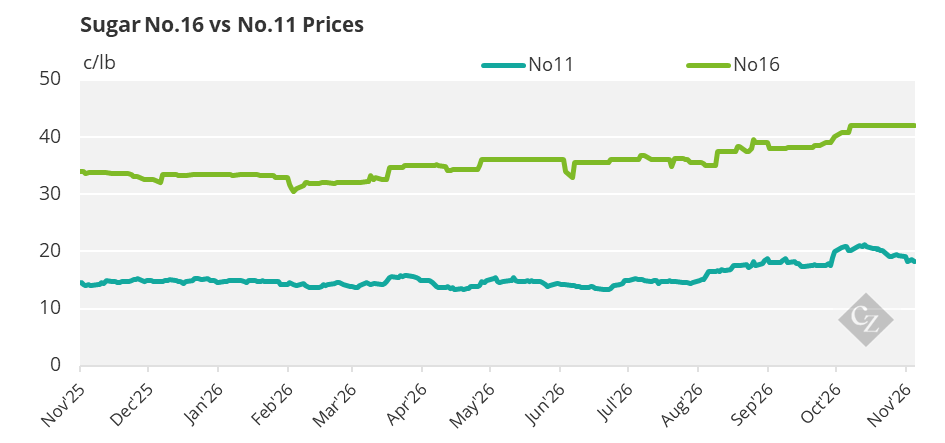
Sales activity was limited. Many users have balked at sharply higher prices, opting to delay purchases in hopes that the market will eventually correct. At the same time, sellers have been hesitant to offer additional tonnage amid growing uncertainty over crop prospects and concerns that little, if any, surplus sugar may be available once the harvest is complete. At least one processor remained out of the market for the time being. Inquiries were steady, though it was unclear whether they reflected genuine demand or growing concern about supply availability.
Deliveries were brisk. Demand from bakeries and confectionery manufacturers accelerated as they built inventories ahead of peak holiday production, resulting in a steady flow of sugar deliveries throughout the month.
Sugar Beet Harvest Nears Completion
The US sugar beet harvest entered its final stretch, with some growing regions approaching completion and others already wrapping up fieldwork. After delaying harvest to maximize sugar accumulation and await much-needed moisture, growers shifted their focus to lifting beets before the onset of freezing weather.
In an ironic twist, rain showers that many producers had hoped for throughout much of the growing season finally began to materialise, slowing fieldwork just as the industry raced to finish digging the crop. With forecasts calling for colder weather later this month, market participants remained keenly aware that prolonged wet conditions could delay harvest progress and increase the risk of beets remaining in the ground ahead of a freeze.
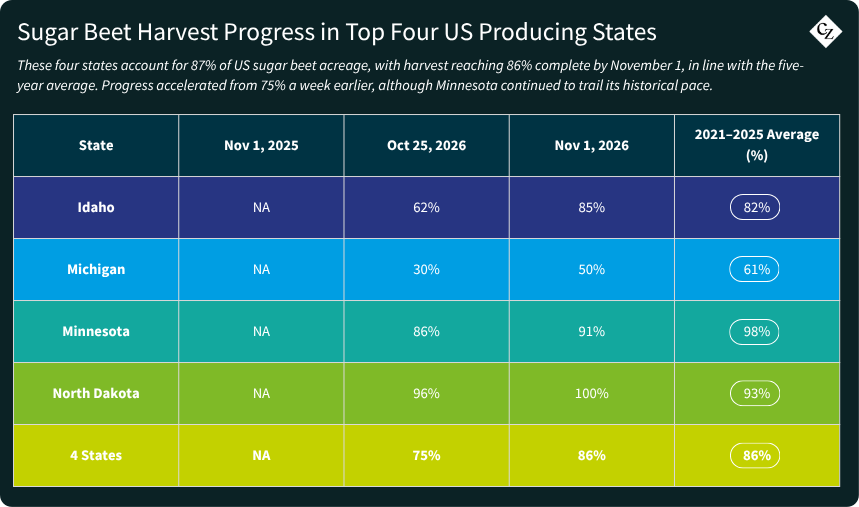
The USDA said that, as of November 1, harvest completion was at 91% in Minnesota (86% a week earlier, 98% as the 2021-25 average), 100% in North Dakota (96%, 93%), 85% in Idaho (62%, 82%), 50% in Michigan (30%, 61%), 89% in Colorado (75%, 81%) and 85% in Wyoming (76%, 90%). The sugar cane harvest in Louisiana, at 40% complete as of November 1, was ahead of the average pace of 32%.
The USDA does not provide harvest updates on the sugar cane crop in Florida, but one trade source indicated that output has been adversely affected by pasture mealybug infestations, resulting in a notable reduction in available sugar cane supplies compared with prior seasons.
Policy Uncertainty Weighs on Market Sentiment
Also adding uncertainty to market sentiment were the recent US midterm elections, with participants speculating about potential changes to food assistance, nutrition policies and tariff measures, although the extent and timing of any policy shifts remained uncertain.
Activity in the corn sweetener market began to stall, as the persistent downslide in corn futures appeared to provide leverage to buyers seeking more advantageous offers.