Insight Focus
US cash sugar prices remained firm despite softer demand forecasts. The USDA raised its sugar stocks outlook while harvest progress advanced across key beet-producing states. Ongoing buyer interest and limited supply availability continued to support the US market.
This update is from Sosland Publishing’s Sweetener Report. For more information and subscription details, CLICK HERE.
Demand Signals Support Firm US Sugar Market
Strength in the cash sugar market prevailed this week, as access to supplies remained limited amid indications of underlying demand. Most sellers continued to withhold offers for 2027 contracts. Prices were unchanged but maintained a firm tone.
While much of the market’s attention remained focused on the size of this year’s crop, participants also weighed the outlook for demand. In a year that began with Robert F. Kennedy Jr., US Secretary of Health and Human Services, declaring a “war on added sugar,” consumers have since faced mounting inflationary pressures, forcing many to balance health-conscious purchasing decisions against tightening household budgets.
Some sellers have pointed to the steady stream of inquiries for 2027 supplies as evidence that demand remains intact, although several other factors have likely contributed to the increased buying interest.
Rising fuel and transportation costs may have prompted some users to seek alternative suppliers to reduce freight expenses.
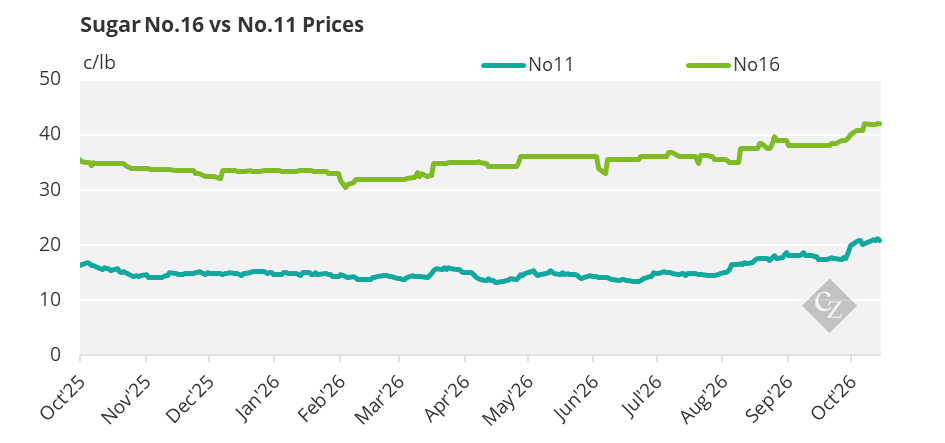
At the same time, firmness in the global sugar market, where tightening production outlooks have heightened concerns about supply availability, has lent support to domestic values. As a result, some buyers have sought additional coverage to lock in US prices, while others have moved to limit their exposure to potentially higher-priced imported supplies.
USDA Raises Sugar Stocks Outlook Despite Lower Demand Forecasts
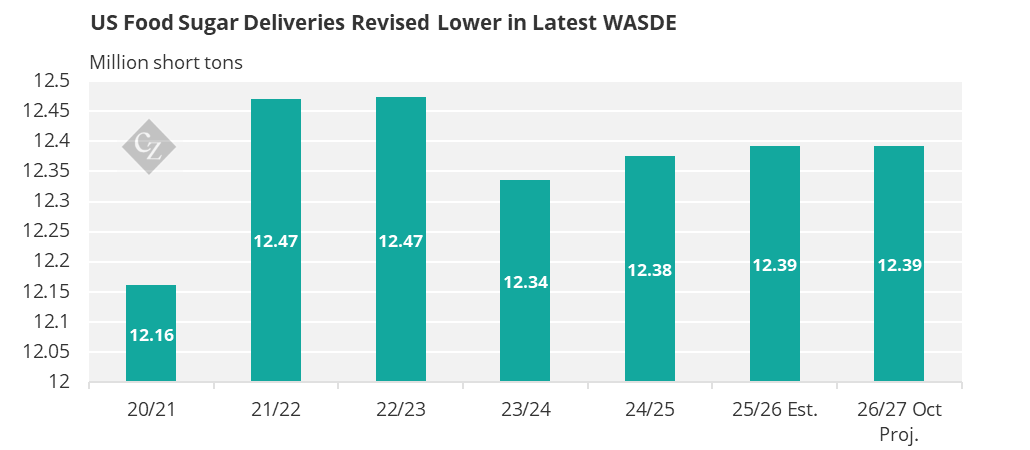
The latest WASDE report from the USDA provided some insight into the demand outlook. In the October 9 report, the department lowered both the 2025-26 estimate and the 2026-27 forecast for food-based deliveries to 12.392 million short tons (11.241 million tonnes), down approximately 49,000 short tons from September but still about 17,000 short tons higher than the 13.375 million short tons estimated in 2024-25.
Source: USDA
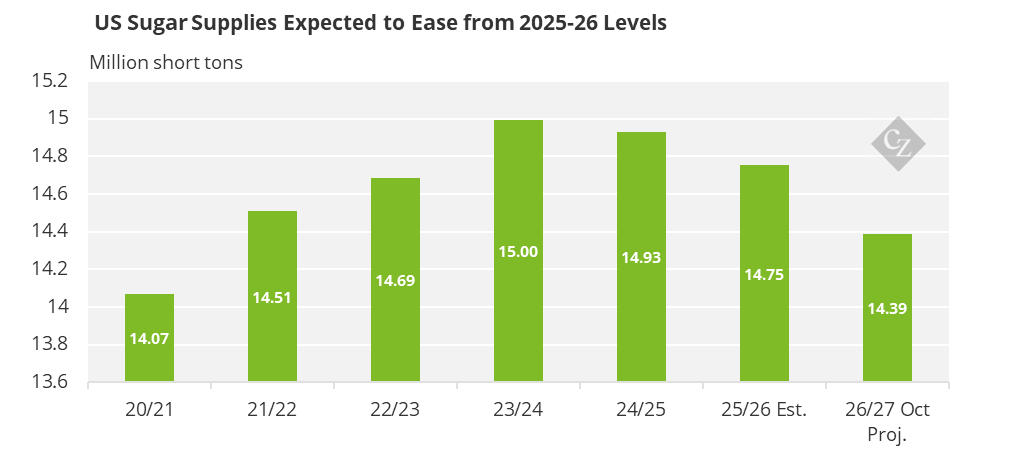
As for supply, the USDA estimated total US sugar supply in 2025-26 at 14.753 million short tons, up 149,000 short tons from September but down 178,000 short tons from 2024-25. Total US sugar supply in 2026-27 was forecast at 14.387 million short tons, up 119,000 short tons from September but down 366,000 short tons from 2025-26.
Source: USDA
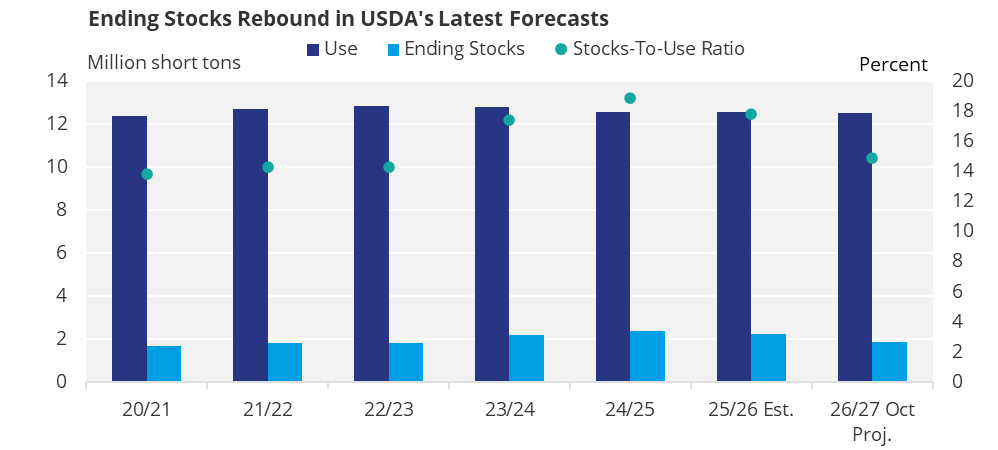
Sugar ending stocks in 2026-27 were forecast at 1.865 million short tons, up 168,000 short tons, or 10%, from September but down 366,000 short tons, or 16%, from 2025-26. The ending stocks-to-use ratio was set at 14.9%, up from 13.5% in September but down from 17.8% in 2025-26.
Source: USDA
Sugar Beet Harvest Gains Pace Across Key Producing States
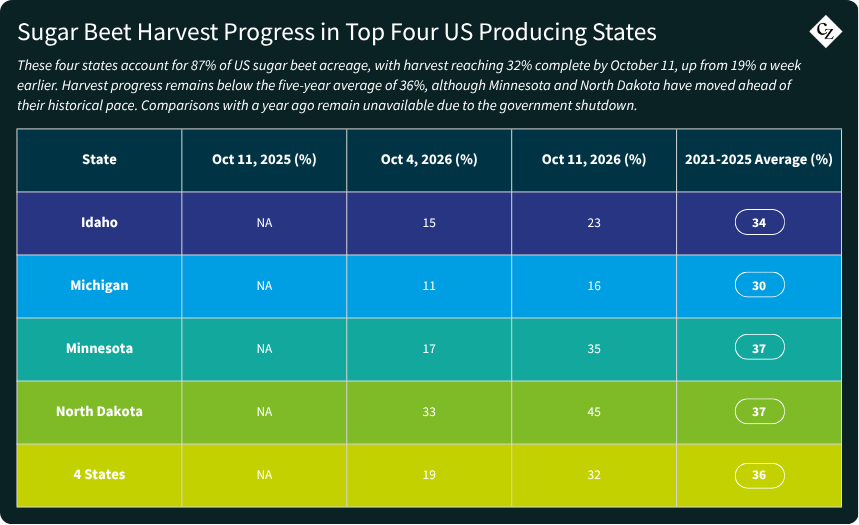
Harvest progress advanced, but most states continued to lag the five-year average pace. Harvest completion as of Oct. 11 stood at 35% in Minnesota (compared with the 2021-25 average of 37%), 45% in North Dakota (37%), 23% in Idaho (34%), 16% in Michigan (30%), 29% in Colorado (50%), 40% in Wyoming (55%), and 16% in Louisiana (13%).
The domestic corn sweetener market was active, with negotiations for 2027 annual contracts underway. Recent bearish USDA reports on corn provided fresh incentives for buyers to negotiate lower values.