Insight Focus
Container freight rates peaked in early July. This was driven by multiple factors, including strong Transpacific demand, constrained capacity and front-loading ahead of US tariffs. Drewry’s World Container Index reached highs not seen since September 2024. Rates cooled slightly later in the month but remained elevated due to geopolitical disruptions.
Freight Rally Peaks
Container freight rates strengthened sharply during the first half of July as an early peak season collided with constrained capacity. Drewry’s World Container Index (WCI) rose to USD 4,639/FEU on July 9, its highest level since September 2024. Shanghai–Los Angeles rates climbed to a high of roughly USD 6,482/FEU, while Shanghai–New York remained near USD 7,900/FEU.
Asia–Europe routes also strengthened, with Shanghai–Rotterdam approaching USD 4,900/FEU and Shanghai–Genoa exceeding USD 6,400/FEU.
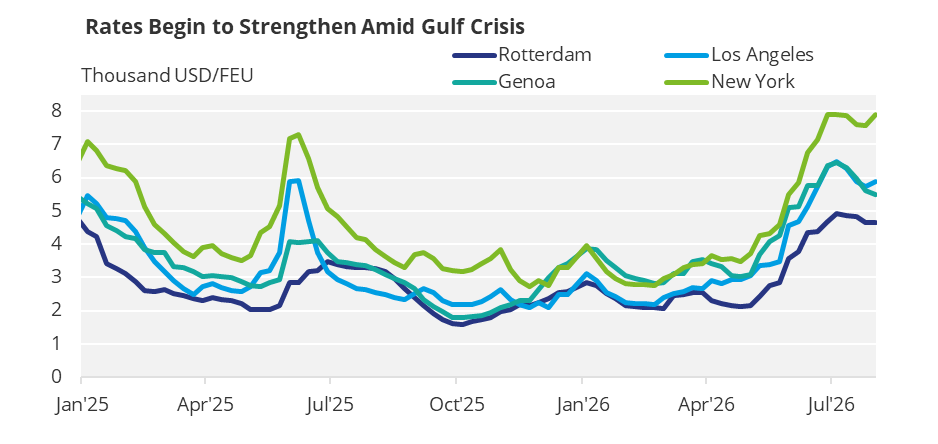
Source: Drewry
By the second half of the month, however, the market began to cool. Drewry’s composite index fell to around USD 4,374/FEU by July 23, marking the first significant correction after ten consecutive weeks of gains. Despite the decline, pricing remained well above historical norms and transpacific routes proved considerably more resilient than Asia–Europe services.
Carriers continued to support rates through General Rate Increases (GRIs), peak-season surcharges and capacity discipline. Several lines announced mid-July surcharges ranging from USD 2,000-3,000/FEU on transpacific routes, signalling ongoing confidence that spot markets would remain elevated.
Front-Loading Dominates
Trade flows during July were heavily influenced by importers accelerating cargo movements ahead of tariff deadlines and potential policy changes in the US. Several market reports noted that US inbound container volumes rose significantly as retailers and manufacturers front-loaded inventories for the second half of the year. One estimate suggested inbound US volumes increased about 15% month-on-month as cargo was pulled forward from later quarters.
The strongest flows were observed on transpacific lanes. US import demand remained focused on West Coast gateways, particularly Los Angeles and Long Beach, although East and Gulf Coast ports also captured additional volume. Imports from China remained robust despite continuing geopolitical tensions, helping sustain vessel utilisation and freight pricing.
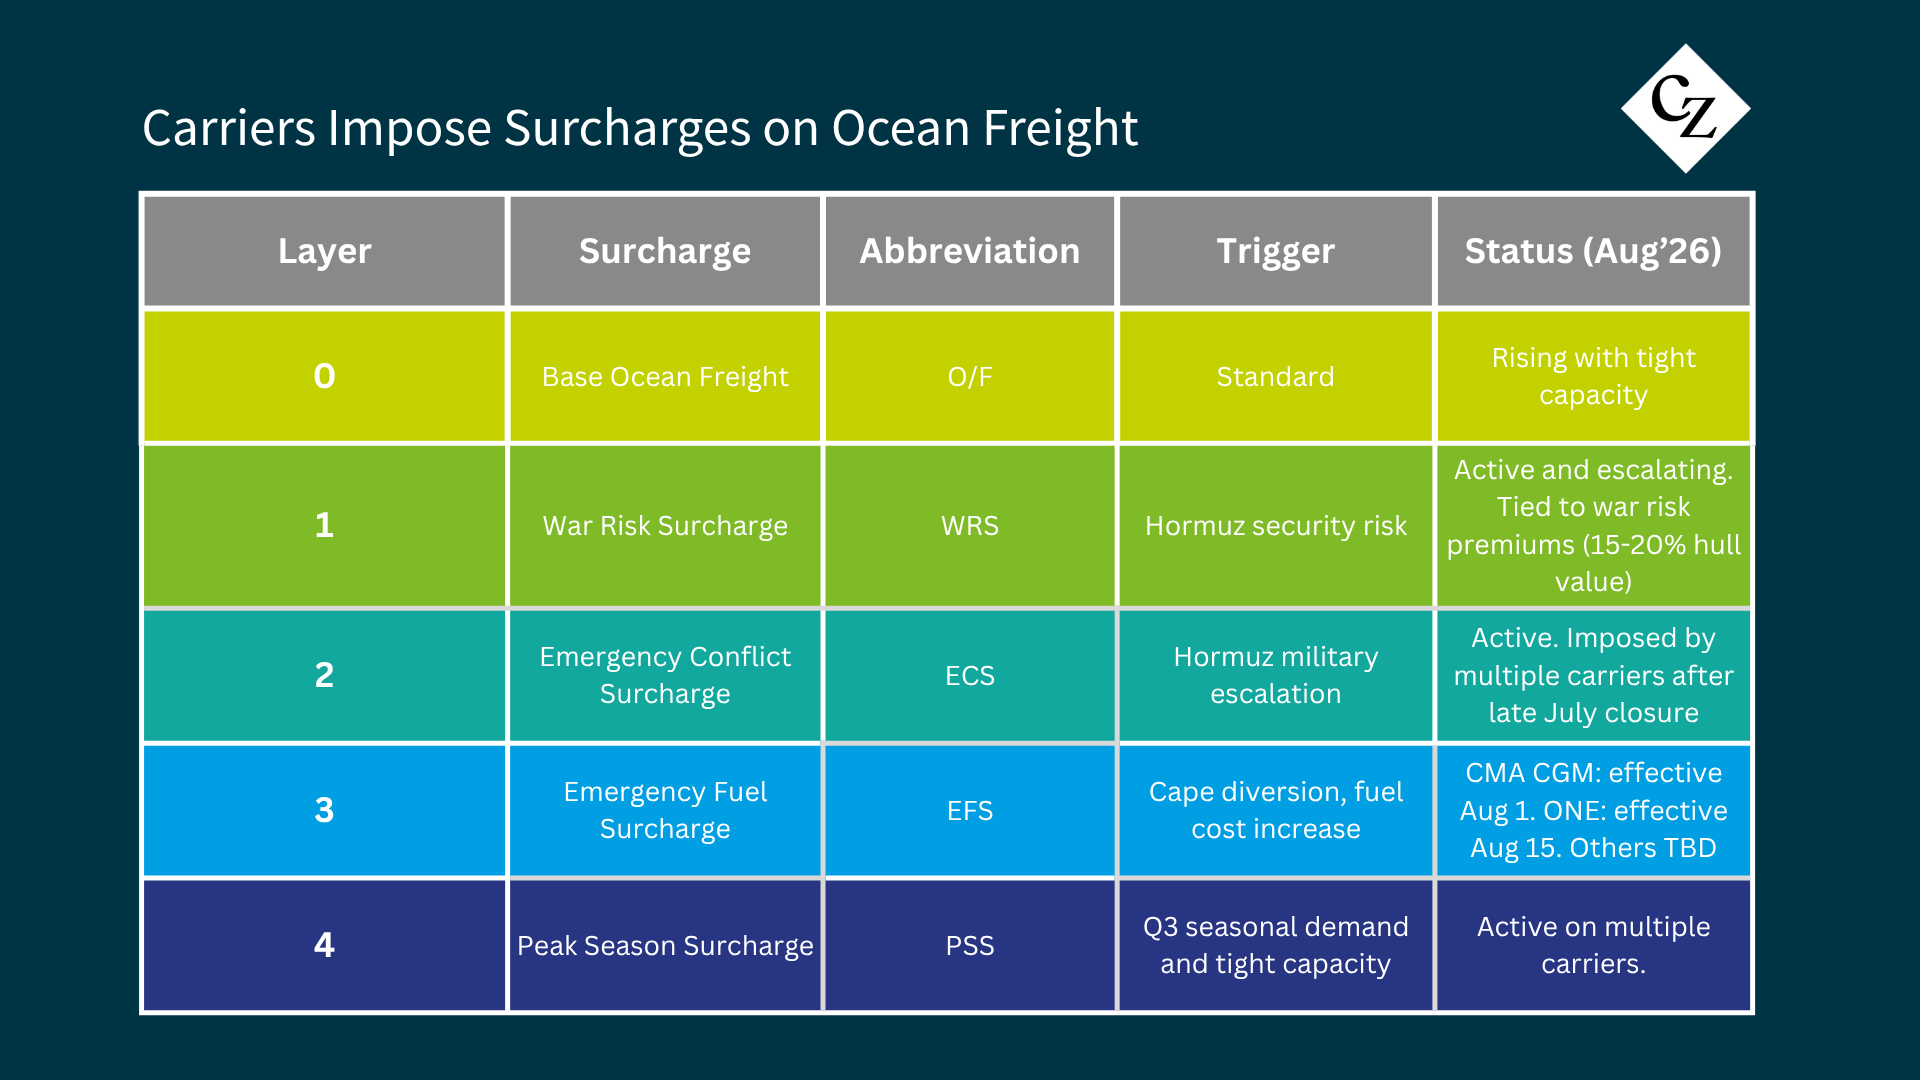
Meanwhile, Asia–Europe demand was supported by cargo diversions caused by continued disruption in Middle Eastern shipping corridors and the Red Sea. However, some July reports suggested that peak-season cargo had effectively started in May and June, reducing booking momentum toward the end of July.
Route Gaps Create Opportunities
One of July’s defining characteristics was the growing divergence between trade lanes. Transpacific routes consistently outperformed Asia–Europe services, creating significantly different pricing environments for shippers.
Shanghai–New York commanded a premium of more than USD 3,000/FEU over Shanghai–Rotterdam during much of the month, reflecting stronger US import demand and tighter capacity. Mediterranean routes also held firm relative to Northern Europe because Red Sea diversions reduced effective vessel supply.
Shipping lines increasingly prioritised vessel deployment on higher-yield transpacific trades, while capacity additions and extra-loader services were directed toward North America. At the same time, some shippers shifted sourcing and export activity toward Southeast Asia as supply chains continued to diversify away from China, supporting regional freight demand.
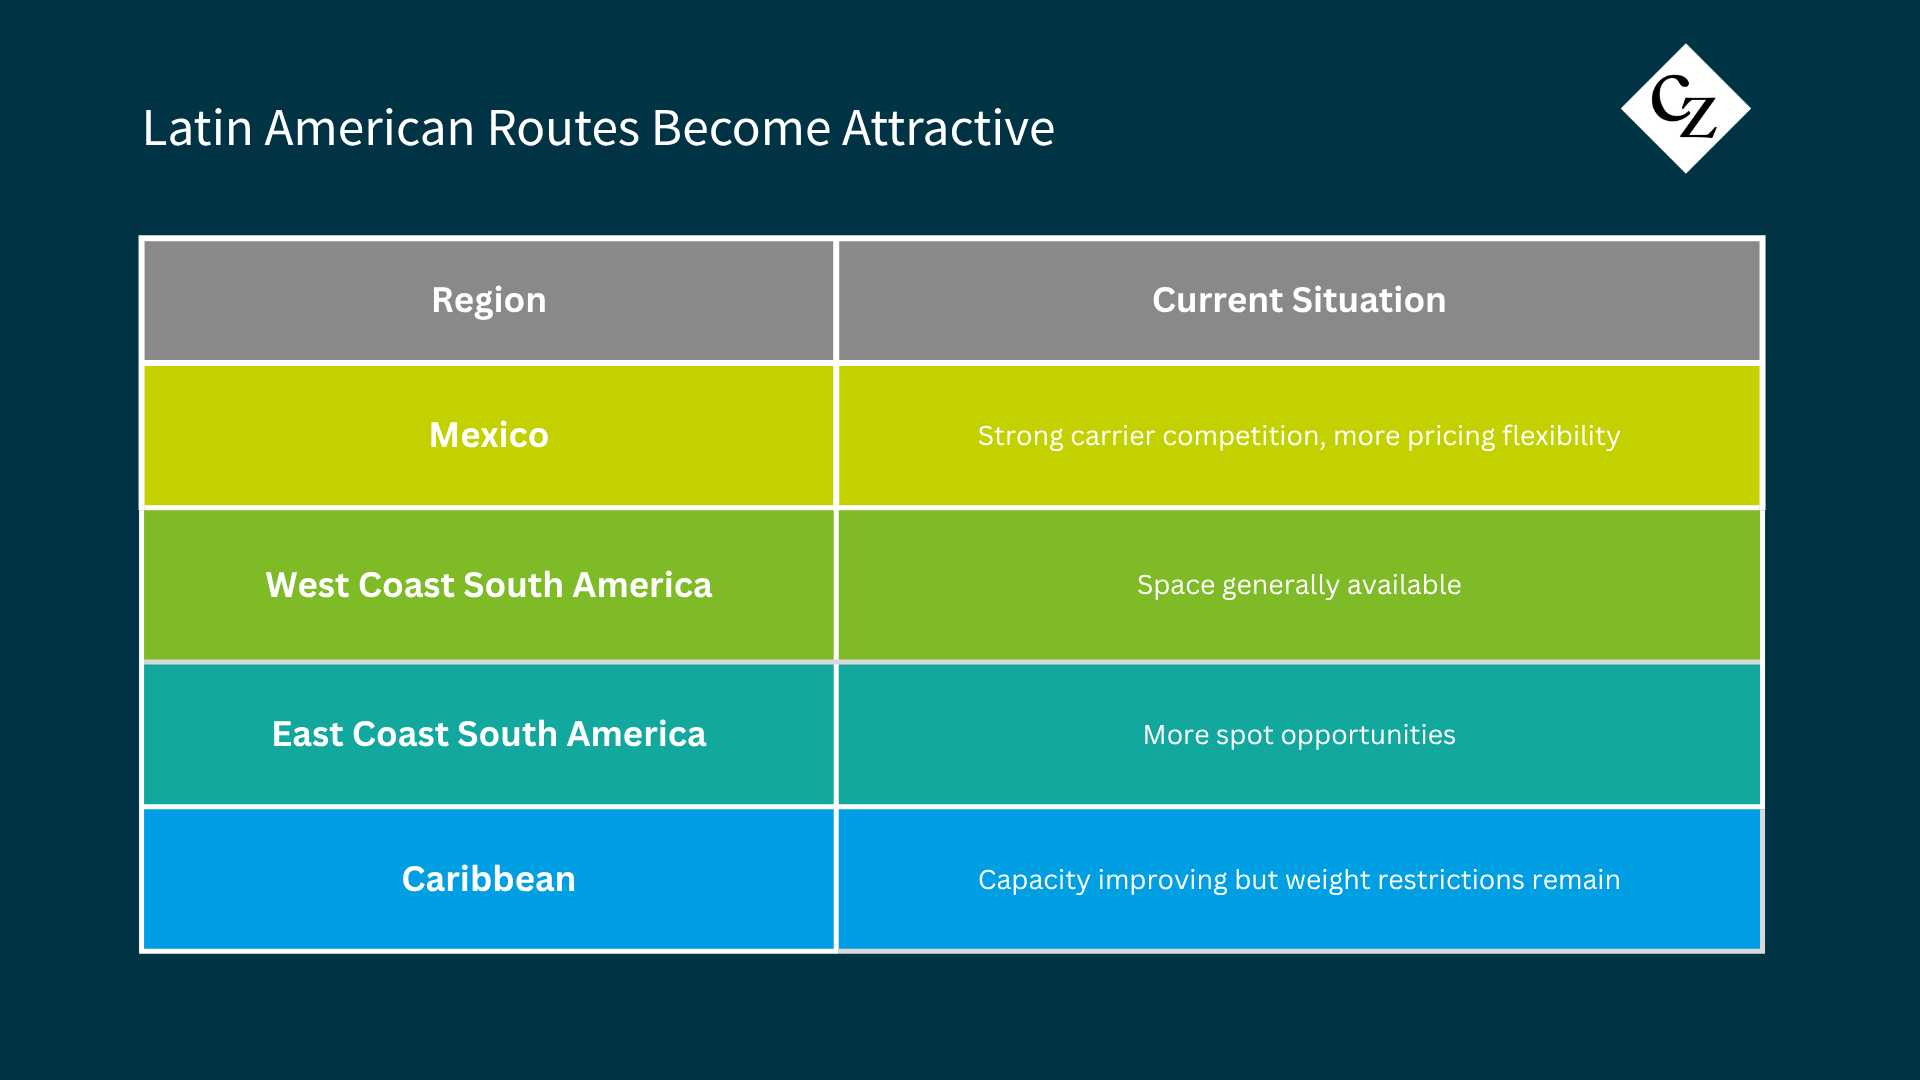
Latin American routes also became comparatively attractive as some July market updates reported more competitive spot pricing than was available on major East-West trades.
Capacity Remains Tight
Despite significant vessel deliveries globally, effective supply remained constrained throughout July. Continued diversion around Africa rather than through the Suez Canal lengthened voyage times and absorbed large amounts of capacity. Security concerns around the Strait of Hormuz and broader Middle East tensions further reduced network flexibility and increased operational costs.
Equipment shortages remained a recurring issue, particularly for 40-foot containers across China and Southeast Asia. Blank sailings and selective capacity withdrawals also limited available space, even as carriers introduced extra-loader vessels on some routes. Approximately 30 blank sailings were reported across a five-week period in the transpacific market.
By late July, evidence suggested that the market had reached its cyclical peak. Additional carrier capacity, softer booking momentum and the completion of much of the tariff-related front-loading began easing pressure. Nevertheless, rates remained elevated because geopolitical disruptions and extended sailing distances continued to absorb substantial vessel capacity.