Insight Focus
Global dairy markets remain divided by product rather than direction. With Algeria absorbing substantial WMP volumes, US dairy entering New Zealand and FFMP following SMP higher, the next shift in dairy availability may be driven by processors’ response to current price signals.
The global dairy market is not short of milk in aggregate. Production has expanded across several major exporting regions, including New Zealand and the US. Yet individual dairy products continue to move in sharply different directions.
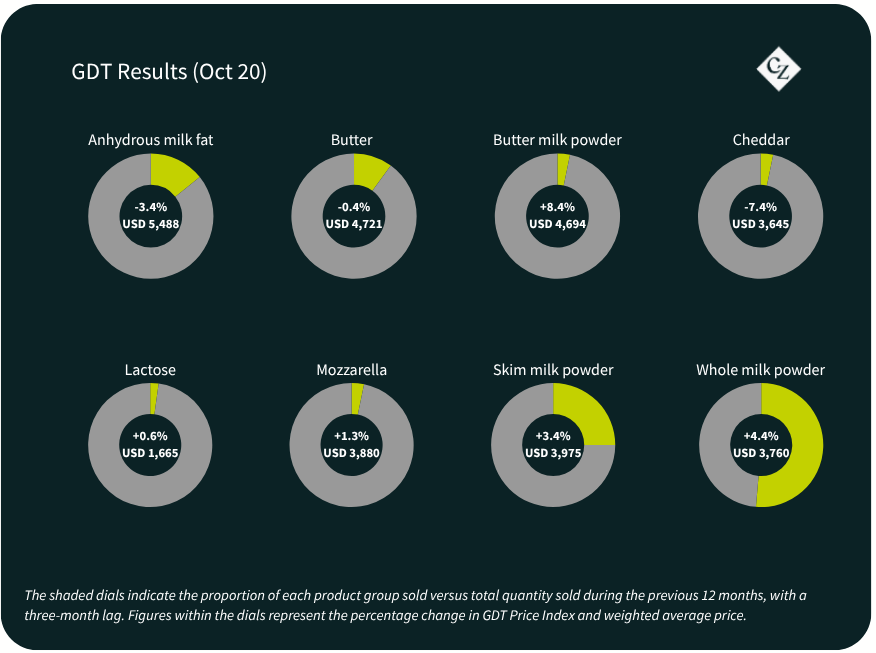
That divergence was evident at the October 20 GDT event. WMP rose 4.4% and SMP increased 3.4%, while cheddar fell 7.4%, butter slipped 0.4% and AMF declined 3.4%. The overall index increased, but the result was a rotation between products rather than evidence of a broad dairy rally.
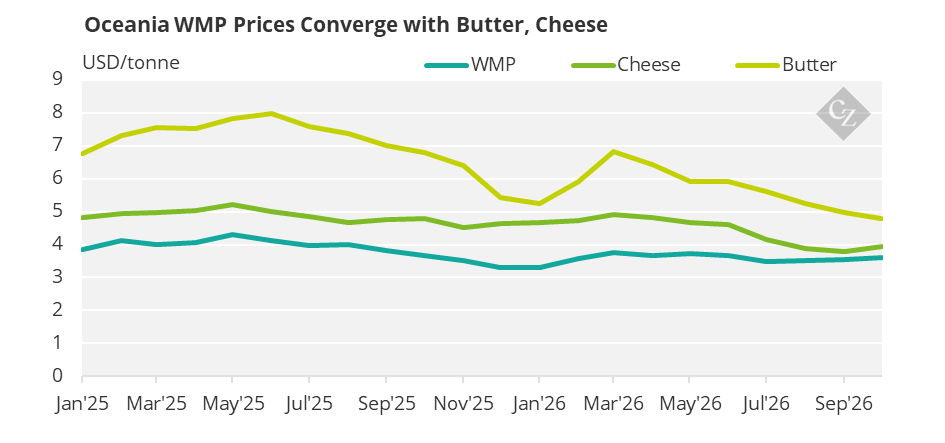
The latest developments in New Zealand help explain why that distinction matters. The country reportedly reached peak milk day earlier this season, particularly in Waikato. At the same time, declines in cheddar and WPC returns, combined with firmer WMP, have brought the NZ cheddar/WPC stream back to parity with WMP.
WMP has not necessarily overtaken every alternative use for milk. In particular, its return relative to the SMP and milkfat stream remains uncertain. However, parity with cheddar/WPC removes one competing incentive for milk and may alter the product mix during the post-peak portion of the season.
Strong Opening, Earlier Peak
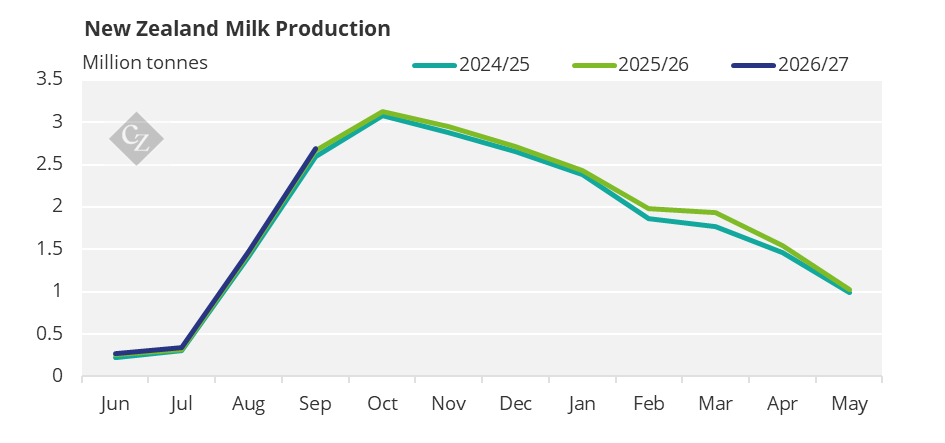
New Zealand milk production began the season strongly. However, an early national peak changes the shape of the production curve and places more importance on the rate of the subsequent decline.
Source: CLAL
The season may still produce strong overall collections; an earlier peak alone does not imply weaker full-season output. However, it makes projecting the strong opening pace across the rest of the season less reliable, especially if North Island conditions deteriorate.
This matters because processors are making product-allocation decisions with progressively less peak-season milk available. The question is no longer simply how much milk New Zealand produces. It is how much milk remains after the seasonal peak, and which product stream offers the best return at that point.
WMP Regains Ground Against Cheddar and WPC
Until recently, stronger cheddar and WPC economics provided an incentive to direct milk solids toward the combined cheese and whey protein stream. Declines in both product values have now reportedly brought that stream back to parity with WMP.
This does not establish that WMP is New Zealand’s highest-returning stream. The relative economics of WMP against SMP and milkfat also need to be considered. Nevertheless, WMP no longer appears to carry the same return disadvantage against cheddar/WPC.
Source: CLAL
If current relationships persist, processors may produce more WMP and less cheddar and WPC than they otherwise would have. This would represent a supply response to firmer WMP pricing, but it could also transfer some availability pressure into cheese and whey proteins.
That is an important distinction. More WMP production would not mean that New Zealand has produced more milk. It would mean the same pool of milk solids had been allocated differently.
Algerian Demand Gives WMP a Firm Anchor
The change in relative returns follows a significant purchase by Algeria’s state buying agency, ONIL.
Market reports indicate that ONIL purchased approximately 25,000 tonnes of WMP at its latest tender. Around 21,000 tonnes were reportedly awarded to NZ origin suppliers, with the balance divided among Adecoagro and other suppliers.
The result converts anticipated Algerian demand into a substantial physical purchase. It also appears to have required product from several suppliers and origins rather than revealing abundant nearby availability from any one source.
It is believed that some producers were reluctant to offer substantial discounts in this tender because of perceived market tightness. South American suppliers also reportedly offered SMP into the tender, which is unusual. This occurred against an already firm international SMP market and suggests that North African demand is influencing a broader range of milk powders, not WMP alone.
FFMP Is Providing Less Price Relief
Fat-filled milk powder would normally offer buyers a lower-cost substitute when WMP prices rise. However, that substitution option is also becoming more expensive.
Expana has raised its European FFMP assessment to approximately EUR 3,300/tonne. Expana said stronger demand and tight supply had caused FFMP to follow SMP higher. It also attributed SMP firmness to demand from Africa and Asia-Pacific, alongside limited participation by US and South American sellers.
FFMP remains cheaper than WMP, and formulations and applications differ between buyers. Nevertheless, the price of the substitute is no longer standing still while WMP rises.
This reinforces the significance of the ONIL purchase. Algerian demand is supporting WMP at the same time that greater demand and limited supply are lifting the price of an important alternative.
US Dairy Is Reaching New Zealand
At the opposite end of the market, lower US prices have reportedly encouraged major New Zealand buyers to book increasing volumes of US-origin cheese and butter, with some agreements extending through the first half of 2027.
That is a notable trade flow. New Zealand is one of the world’s major dairy exporters, but domestic buyers will still import when international price relationships make landed product competitive.
Source: USDA
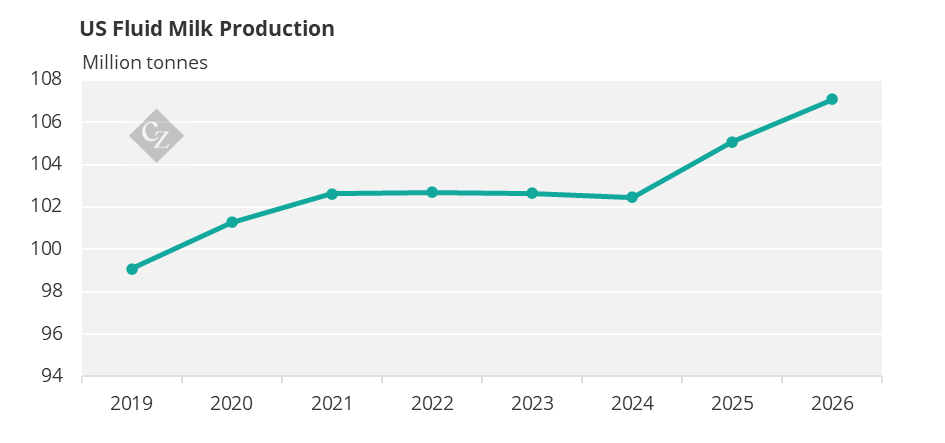
Strong US milk production and substantial cheese availability helped create that opportunity. US September milk production increased by 3% year on year, while an expanding herd added to available supply. The US market consequently became increasingly dependent on exports to absorb its additional production.
However, the economics may already be changing. CME spot cheese has risen sharply over the past two weeks. Trigona’s converted US cheese series increased from EUR 2,529/tonne on October 9 to EUR 3,543/tonne on October 23.
Market participants have linked part of the move to disruption at a major US producer, although the scale and duration of that impact remain unclear. The broader market evidence also points to plant downtime and quality issues affecting cheddar production in parts of the US.
The effect is an example of dairy arbitrage beginning to correct itself. Discounted US cheese attracted additional export demand, including unusual flows into New Zealand. The subsequent price rally is now narrowing the gap that made those flows attractive.
If New Zealand processors allocate less milk to cheddar/WPC at the margin, those imports could remain strategically relevant. But higher CME prices may make future US coverage increasingly expensive.
Butter Prices Hold While Commercial Terms Soften
Butter presents a different version of the same regional divergence.
Fonterra continues to defend NZ butter premiums to GDT, citing Chinese demand. The latest GDT result provided some support for that position: butter declined only 0.4%, despite weaker results in AMF.
At the same time, butter tonnage has been added to upcoming GDT events and NZ suppliers are reportedly offering more flexible payment terms to Butter buyers in markets previously perceived as riskier.
These signals are not necessarily contradictory. Chinese demand may be sufficient to support the GDT benchmark, while placing additional product in other destinations requires greater commercial flexibility.
“The price is firm, but the terms are softening.”
This suggests that the premium for NZ butter remains defensible in some channels but is not uniformly supported across all buyers and destinations.
Demand Diverging by Urgency and Affordability
Algeria is buying because physical stock requirements create urgency. The Philippines offers the opposing case.
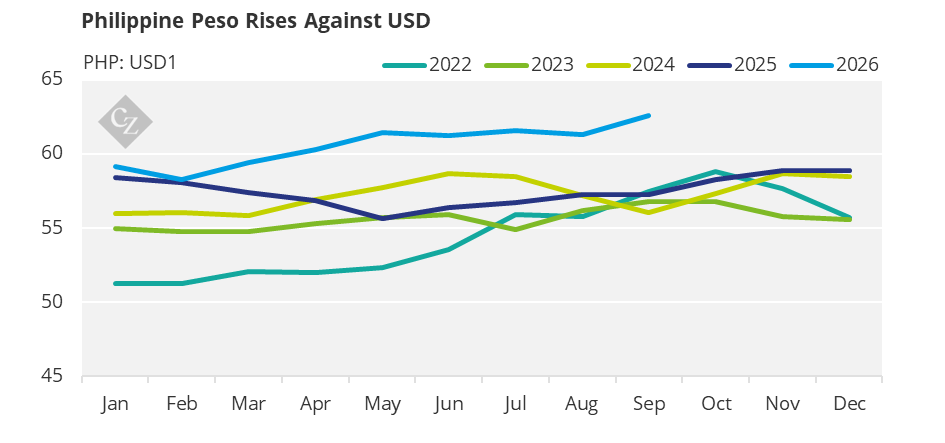
Philippine dairy demand is currently quiet, with the weaker peso affecting purchasing decisions. Buyers are evaluating offers for January and February departure rather than rushing to cover prompt requirements. Cheese interest remains possible, but buyers are seeking sharper prices following the decline at the latest GDT event.
Source: Bangkok Central Bank
The contrast is instructive. Algeria’s inventory requirements have forced demand into the market despite firm pricing. In the Philippines, currency pressure is allowing or requiring buyers to delay decisions.
This is not evidence of one global demand cycle. Demand is being shaped by local inventory, foreign exchange and the ability of buyers to postpone coverage.
Allocation, Not Aggregate Milk, Remains the Key
The latest evidence does not point to a broad dairy rally. Nor does it indicate that the world is running out of milk.
Instead, it shows dairy availability being reshaped by product economics:
-
WMP has regained competitiveness against the NZ cheddar/WPC stream.
-
ONIL has absorbed a substantial volume of WMP.
-
FFMP is following SMP higher, making substitution more expensive.
-
US cheese and butter have reached New Zealand, but the US cheese discount is narrowing.
-
NZ butter premiums are holding in some channels while payment terms become more flexible in others.
-
New Zealand has passed peak milk day earlier, leaving product allocation increasingly dependent on the post-peak milk curve.
If WMP remains competitive against cheddar/WPC, New Zealand processors may direct more milk toward WMP than they otherwise would have. This could help satisfy powder demand, but it may also produce less cheese and whey protein.