Insight Focus
Global milk output is not translating evenly into dairy product availability. The balance now depends less on total milk supply than on how milk components and processing capacity are allocated. Fresh products and higher-value proteins are absorbing skim solids in Europe and the US, limiting SMP, NDM and whey powder. In New Zealand, strong milk flows are encouraging maximum WMP throughput and buyers are responding through substitution, earlier purchasing and alternative origins.
Global dairy markets are presenting an unusual contradiction. Milk production is improving in some major exporting regions, yet several powders and protein ingredients remain difficult or expensive to source.
The explanation lies in what happens after milk reaches the factory. Processors are directing milk and its components toward the products offering the strongest demand, best returns or most efficient use of constrained capacity. This creates abundance in some parts of the dairy complex and scarcity in others.
In Europe and the US, more skimmed milk concentrate is being absorbed by fresh products such as yoghurt, leaving less available for SMP and NDM drying. Strong demand for high-protein products is also pulling processing streams away from conventional powders. Meanwhile, New Zealand’s strong early-season milk flows appear likely to encourage heavy WMP production, creating a different constraint: lactose availability.
Milk Supply No Longer a Sufficient Market Indicator
The volume of milk produced is only the first step in determining dairy ingredient availability. Where that milk is directed, and which products processors choose to prioritise, can matter just as much.
In Europe, recent hot weather reduced milk volumes and SMP production. At the same time, fresh dairy demand has absorbed more skimmed milk concentrate and finished SMP. In the US, skim streams have similarly been pulled toward products such as yoghurt and cottage cheese, reducing the amount available to balancing plants and dryers.
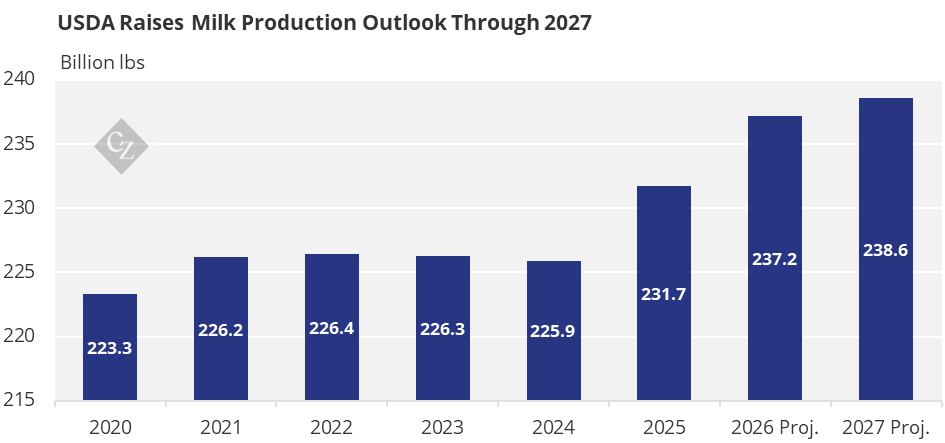
Recent US market reports show that this is occurring even as national milk production remains above year-ago levels. More milk does not automatically resolve a shortage when the incremental volume is committed to another product category.
Source: USDA
Processors Are Creating Different Product Balances
This allocation effect is most visible in the widening divide across the dry dairy complex. SMP and NDM availability has tightened, while conventional whey powder output has been limited as processors favour higher-value protein products. However, the protein complex is not moving uniformly: WPI and some lower-protein WPC grades remain tight, while additional production has allowed WPC80 to ease from its earlier highs.
Operational disruptions have amplified the near-term pressure. Industry contacts report a salmonella-related issue at a large US processor and the temporary shutdown of an MPC dryer at a major New Zealand processor. In a market already constrained by specialised filtration and drying capacity, individual outages can have an outsized effect on availability.
Butter provides a contrast. Market sentiment remains broadly bearish and European inventories are understood to be comfortable, although some buyers report difficulty obtaining meaningful offers at the lowest published indications.
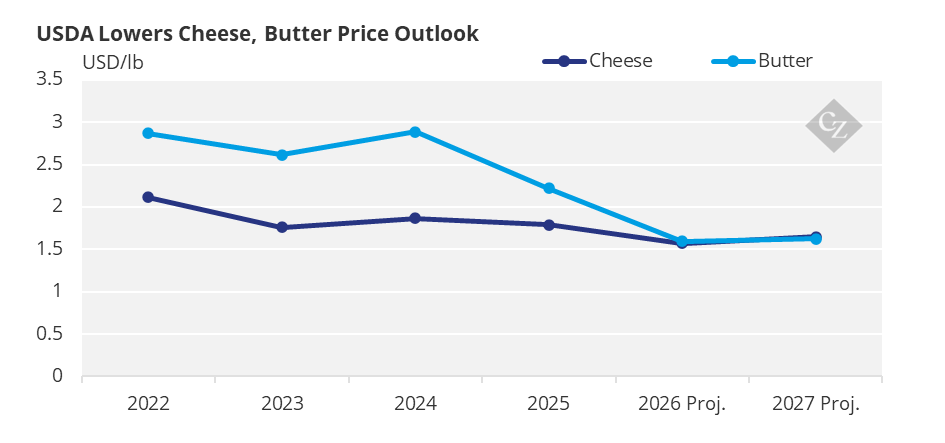
The different signals across butter, SMP and protein ingredients reinforce the same point: the market is balancing individual milk components, not simply total milk.
High Relative Prices Are Forcing Reformulation
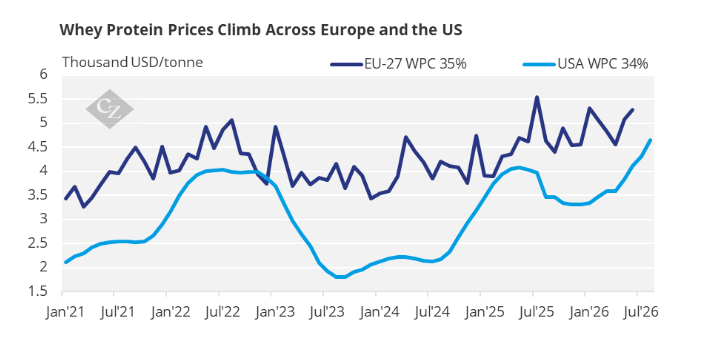
Buyers are responding to these imbalances by reconsidering formulations. Where whey-specific functionality is not essential, MPC can provide a lower-cost source of dairy protein than WPC. The products are not interchangeable in every application, but partial substitution or blending can reduce exposure to exceptionally expensive whey proteins.
Source: CLAL
A similar calculation is now appearing further down the protein scale. Some market participants are evaluating SMP plus whey permeate as a substitute for sweet whey powder where formulations permit. In each case, a distorted relative price creates demand for an alternative ingredient and begins to rebalance the market.
New Zealand Has More Milk, but Its Own Ingredient Constraint
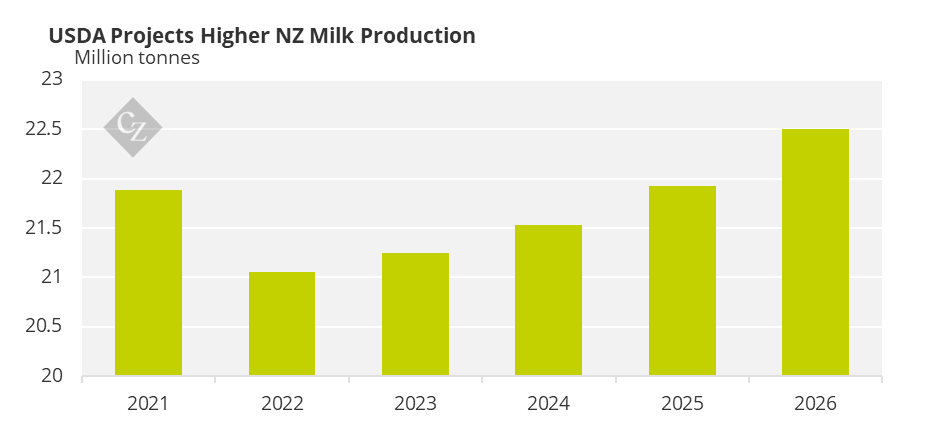
New Zealand illustrates the opposite processing response. Wet conditions have supported expectations for strong early-season milk flows, and industry contacts report that tanker volumes are moving from the South Island to the North Island because southern processing capacity is fully utilised.
When seasonal milk is abundant, WMP provides an efficient way to maximise plant throughput. That supports expectations for heavy WMP production and remains an important bearish influence on the market, particularly if Chinese demand stays subdued.
Source: USDA
However, maximum WMP output creates demand elsewhere in the production system. At least one large New Zealand processor is reported to be short of lactose, consistent with a high WMP manufacturing programme. Market contacts indicate that lactose availability for 2026 shipment is now extremely limited. More milk is therefore increasing the supply of one powder while tightening an ingredient required to produce it.
Demand Reallocated Across Regions
Buyers are adapting geographically as well as technically. Ramadan procurement has accelerated earlier than usual, bringing Middle Eastern demand forward and helping offset weaker anecdotal Chinese buying. North Africa has also attracted new butter buyers following relatively competitive European and Latin American pricing.
Algeria remains especially active. The recent Soummam tender was concluded at aggressive levels, while market contacts report significant volumes of Belarusian product moving into the country. This is commercially relevant because it adds another competitive origin, although unverified explanations about the legal route used by EU-linked companies should not be treated as established fact.
Regional views on WMP remain divided. Asian participants appear more cautious than buyers in the Middle East and Europe. This has been reflected in a recurring futures pattern, with WMP sold down early in sessions before recovering later as Western participants become more active.
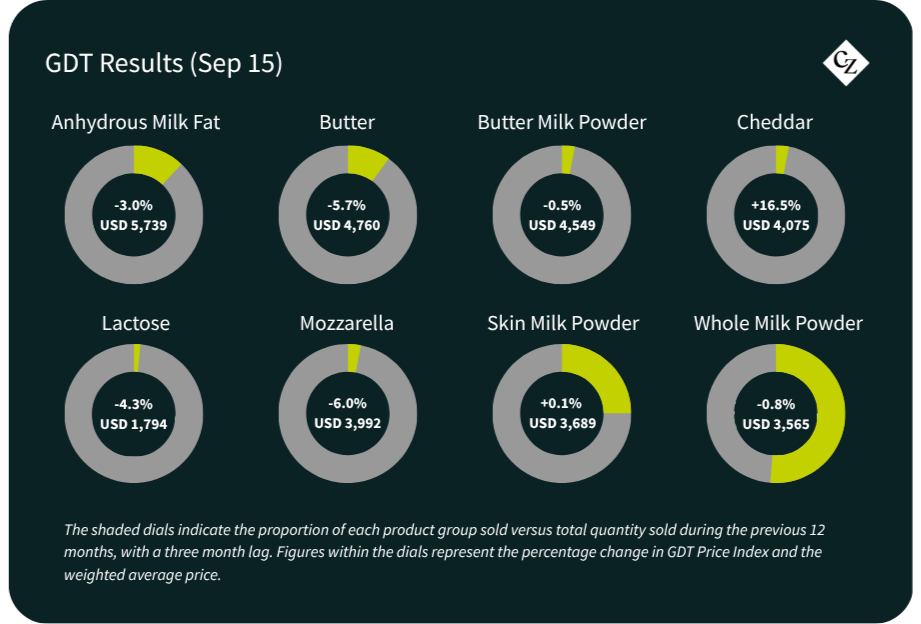
These regional and timing differences are helping the physical market absorb supply that might otherwise weigh more heavily on prices. The bearish WMP case has not disappeared, but its transmission is being delayed or diluted by demand arriving from different buyers and at different times.
The Market Question Has Changed
Dairy markets are not responding to higher milk supply in a uniform way. Milk is being pulled toward fresh products in some regions, channelled into WMP in others and increasingly separated into higher-value protein streams. Each decision changes the availability of another component or ingredient.
Buyers are adapting just as quickly, reformulating products, bringing forward seasonal purchases and sourcing from different origins. This helps explain why bearish headline fundamentals have not produced a broad correction across the dairy complex.
The key question is therefore no longer simply whether the world has enough milk. It is whether that milk is being converted into the products, specifications and locations where buyers need it.