Insight Focus
Nonfat dry milk rallies as milk supplies begin tightening. NDM prices climbed on renewed concerns about milk availability, while whey markets diverged as WPI remained firm and WPC 80% softened. Butter prices weakened on ample inventories and rising milkfat production, while steady cheese output and export demand continued to support the cheese market.
This update is from Sosland Publishing’s Dairy Report. For more information and subscription details, CLICK HERE.
Dairy markets were irregular this week, with nonfat dry milk prices climbing again after pulling back from an earlier rally. Whey protein markets diverged, while plentiful butter supplies pressured that market.
Milk Availability Concerns Drive Powder Market Higher
Nonfat dry milk prices moved sharply higher as concerns about milk and powder availability resurfaced. Dairy cooperatives in the Midwest and East that were affected by a heatwave earlier this summer had warned that milk supplies might tighten in the second half of the year, and one trader said those predictions appeared to be playing out.
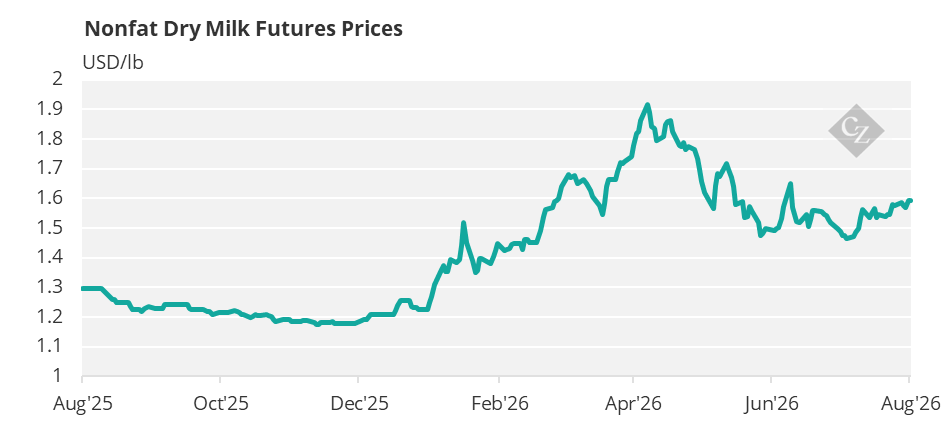
California milk production has also started to slow after remaining relatively strong through much of the summer. Demand may be contributing to the latest price gains, but seasonal buying does not usually emerge until later in the fall. Reopening schools were pulling more milk into Class I uses, leaving less available for drying.
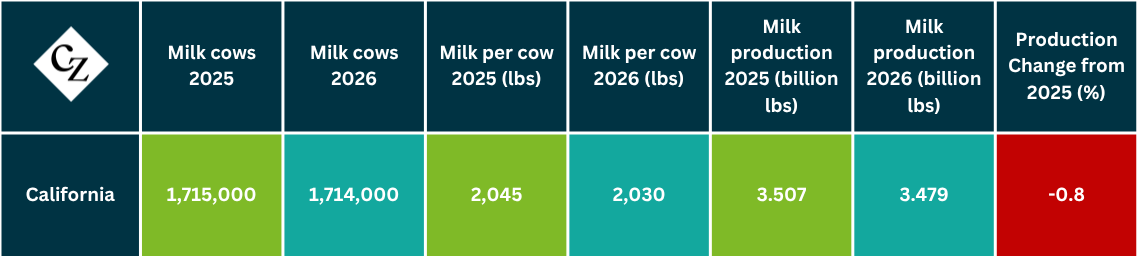
Source: USDA
Whey Markets Diverge as WPC 80% Softens
Whey protein markets were less uniform. Whey protein isolate (WPI) traded around USD 14/lb, while whey protein concentrate (WPC) 80% has fallen from over USD 13/lb to between USD 11 and 12. Manufacturers shifted more production toward WPC 80% when its price moved close to WPI. That additional production is now giving WPC 80% buyers more options and putting some downward pressure on prices.
Meanwhile, WPC 34% values were steady, although supplies remained tight. Some calf milk replacer manufacturers have turned to nonfat dry milk instead.
Butter Market Softens on Strong Inventories
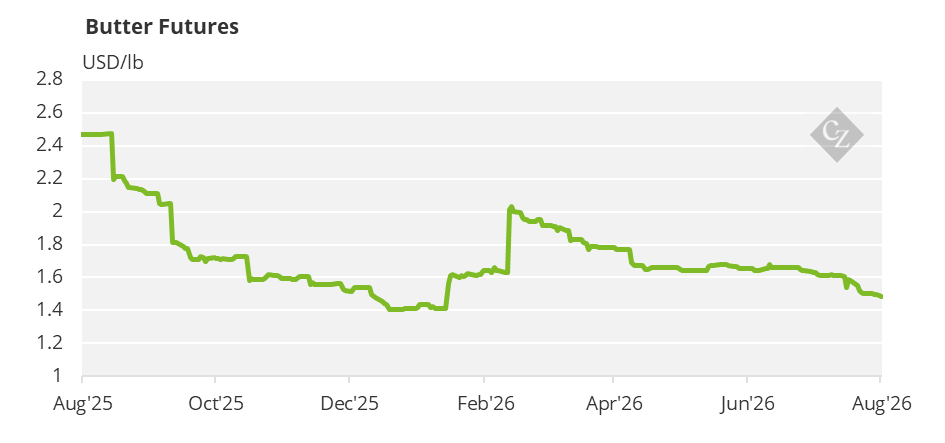
Butter prices came under pressure as supplies exceeded demand. Frozen butter inventories were well stocked, and sellers have consistently offered product on the CME. Export demand also slowed as prices in the world market weakened. One reason for the abundance of butter is the increasing amount of fat in the milk supply. Cows are producing milk with higher fat content than in previous years, giving processors more butterfat to work with even without buying as much cream.
Cheese production continued at a steady pace. Plant downtime made some discounted spot milk available in the Central region. Export interest was solid, although higher US prices made some premium cheeses less competitive overseas.